

 Facebook
 X
 Pinterest
 Copy Link
The 30 Days Between Accepted Offer and Closing in King County
What happens after the seller says yes, who has to do what each week, and the dates that can quietly break your closing.
Most buyers think the hard part ends when the seller accepts the offer. It does not. That is when the clock starts, and a handful of dates in your contract decide whether you close on time or scramble.
I see this from the field every week. I do BPO work across east and south King County, and I am usually in the neighborhood when a deal is in the middle of its 30 days. The deals that go smoothly are not luckier. The buyers simply knew what was coming each week and had their paperwork ready before they were asked.
This is the week-by-week map. It assumes a typical financed purchase of a single-family home, closing in roughly 30 to 45 days. Cash deals move faster. Condos and new construction add steps. Your purchase and sale agreement controls every date, so treat the numbers below as the usual pattern, not a promise.
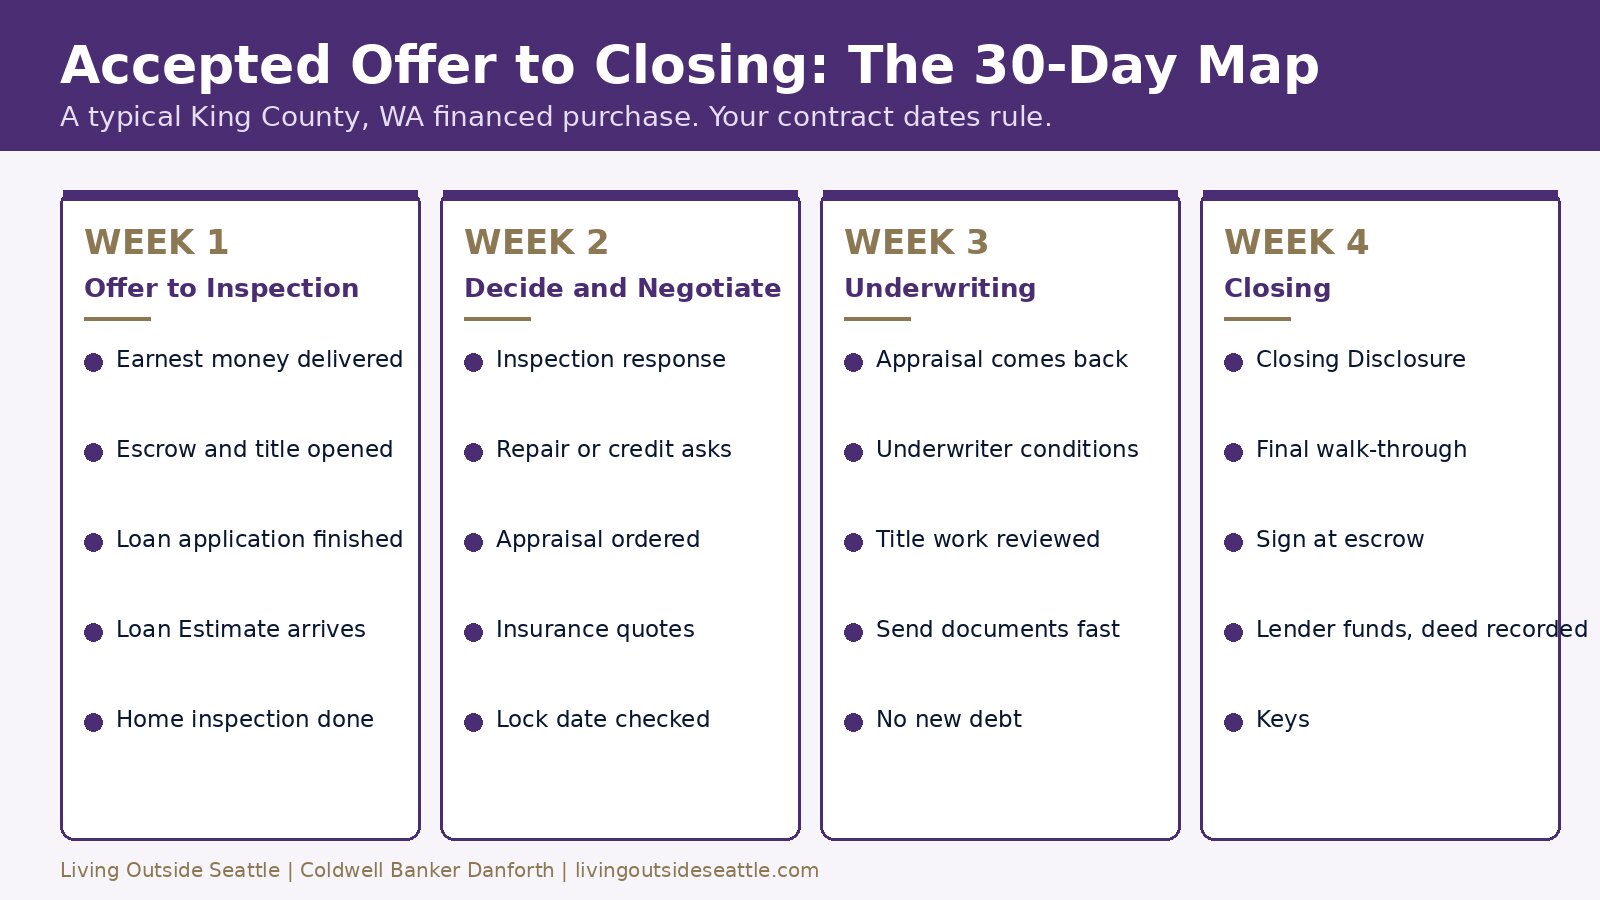
The four weeks between accepted offer and keys, at a glance.
The 30-Day Timeline, Week by Week
Week 1: Get Everything Opened and Inspected
The first few days are about paperwork landing in the right hands. Your earnest money goes to escrow, and the escrow officer opens your file. Escrow is the neutral third party that holds the money and documents until closing. I cover the deposit rules in my earnest money guide, and the short version is this: deliver it on the date in your contract, not the day you remember.
Your lender has work to do too. If you have not finished the full loan application, finish it now. Within three business days of a complete application, federal rules require the lender to send you a Loan Estimate that shows your rate, payment, and cash to close. Read it the day it arrives. So what? It is the first real look at your closing numbers, and errors are easiest to fix early.
The home inspection also usually happens this week. Washington contracts set an inspection deadline, and it is often only about a week out. Book your inspector the same day your offer is accepted. In the Auburn, Kent, and Renton neighborhoods I work in, good inspectors can be booked a week out, and that wait can eat your whole window.
Book the inspector the day your offer is accepted. Good ones fill up.
Week 2: Decide What the Inspection Means
The inspection report lands, and now you have a decision. Under the contract you can accept the home as is, ask for repairs or credits, or in some cases walk away within your inspection period. The deadline matters more than the report. Miss it and you may lose the right to negotiate at all.
My advice is to sort the findings into three piles: safety and major systems, things that are inexpensive to fix, and cosmetic items. Ask for the first pile. Skip the third. I wrote about how sellers see this side in my home inspection seller guide, and knowing how they think helps you ask for things that actually get a yes.
This is also the week your lender orders the appraisal. The appraiser visits the home, compares it to recent sales, and reports a value to the lender. If you are watching a rate lock, check the lock expiration against your closing date now. My rate lock guide explains what extensions cost if closing slips.
Week 3: Underwriting and the Appraisal
Week three is where deals get quiet, and quiet is dangerous. Your file sits with an underwriter, who verifies income, assets, and the property. You may get a list of conditions, which are extra documents or explanations. Answer every one within a day if you can.
The appraisal usually comes back this week. If the value matches or beats your price, nothing changes. If it comes in low, the lender will only loan against the appraised value. Under the usual Washington contract terms, you generally have a short window, often three days, to respond with a notice, so know your date before the report lands. Your options are to renegotiate the price, bring more cash, challenge the appraisal with better comparable sales, or end the deal if your contract allows.
One rule matters more than the rest. Do not open new credit, change jobs, or move large sums of money. A new car loan in week three can change your debt ratio and stall your approval. So what? The lender checks your file again right before closing, and anything new gets noticed.
Week 4: Closing Disclosure, Walk-Through, and Keys
At least three business days before you sign, your lender must deliver the Closing Disclosure. This is the final version of your loan terms and cash to close. Compare it line by line with your Loan Estimate. My buyer closing costs guide lists what each fee is, so you know what to question.
Next comes the final walk-through, usually within a day or two of closing. You are not re-inspecting the home. You are confirming that it is in the agreed condition, that any repairs were done, and that the seller left what they were supposed to leave. Run the faucets, test the outlets, and open the garage door.
Then you sign at escrow. In Washington the lender wires the funds, escrow confirms everything, and the deed is recorded with King County. Possession and keys follow the terms of your contract, which is often the day of recording or the day after. Plan for the keys to arrive later in the day than you hope, and do not schedule movers for early morning.
The Local Angle: What Slows King County Closings
In King County the common delays are not exotic. Inspector calendars fill up. Appraisers in busy stretches of Renton, Kent, and Auburn can take longer to get on the schedule. Condos add a resale certificate and HOA documents. And with mortgage rates above 7% this fall, as I covered in my fall market and mortgage rate post, lock dates and monthly payment limits leave less room for surprises. A month with little slack is a month where one late document matters.
If your closing date is tight, ask your agent and lender to build the plan backward from it. Every deadline in the contract should be on one calendar the day you go under contract.
What This Means for You
If you are about to make an offer, get your pre-approval documents together now, so week one starts fast. If you are already under contract, put every date from your agreement on a single calendar today, including the inspection deadline, the appraisal timeline, the financing dates, and the closing date. Then call your lender and ask what they still need from you. That one call prevents more delays than anything else on this list. If you are a first-time buyer in Kent or nearby, my Kent first-time buyer guide covers the financing side in more depth, and my contingent offer guide explains what changes if you are selling a home to buy this one.
Frequently Asked Questions
How long does it take to close on a house in King County?
Most financed purchases close about 30 to 45 days after the accepted offer. Cash purchases can close in two to three weeks. Your contract sets the closing date, and lenders, appraisers, and inspectors all have to fit inside it.
What happens right after my offer is accepted in Washington?
Your earnest money goes to escrow, escrow opens a file, you finish your loan application, and you schedule the home inspection. Do all four in the first few days, because the inspection and financing deadlines start running from the accepted offer.
What is the most common reason a King County closing is delayed?
Slow documents and calendar conflicts. A late inspection, a late response to an underwriter, an appraisal that takes longer to schedule, or a rate lock that expires before closing can each push a closing date back.
What happens if the appraisal comes in low?
The lender will only loan based on the appraised value. You can usually negotiate the price down, bring extra cash to cover the gap, challenge the appraisal with stronger comparable sales, or end the deal if your contract allows. Watch the notice deadline in your agreement.
Can I get the keys the day I sign?
Not always. Possession follows your contract, and in many Washington deals the deed must be recorded first. That is often the same day or the next day. Ask your agent for the exact possession terms before you book movers.
What should I avoid doing while I wait to close?
Do not open new credit, change jobs, or move large sums between accounts. The lender checks your file again before closing, and a new debt or unexplained deposit can slow or stop your approval.
The 30 days feel long, but they are very manageable when you know the week. Whether you are about to write an offer or you are already in the middle of one, I am happy to walk through your dates and the real numbers with you. No pressure, no sales pitch.
Your guide to life outside Seattle.
253-350-0045 ·
greg@livingoutsideseattle.com ·
www.livingoutsideseattle.com
Simultaneous Closing in Washington State: Escrow & Timing
If you’re selling your current home and buying your next one, a simultaneous closing in Washington State is one of the best ways to avoid two moves, a bridge loan, or a rent-back agreement. It also depends on a chain of deadlines most people never think about until they’re staring at a wire cutoff time on closing morning.
I work with move-up sellers across King County who want to time this right. The mechanics aren’t complicated once you understand the order of operations. But the sequence matters, and one missed cutoff can push your move-in to the next day.
Why a Simultaneous Closing in Washington State Is Hard to Pull Off
Washington uses escrow closings, not table closings. Nobody sits around a conference table exchanging keys and checks. Instead, a neutral escrow company holds everyone’s documents and money, then records the deed and releases funds once every condition is met. Signing happens days before closing. Closing is when funds move and the county records the transfer.
That separation is what makes a same-day sale-and-purchase possible, and also what makes it fragile. Your sale has to fully fund and record before your purchase can use those proceeds. If your sale slips to the afternoon, your purchase slips too, or it doesn’t happen that day at all.
King County’s recording cutoff is typically 10 a.m. for same-day recording. If your buyer’s wire hasn’t hit escrow by then, your sale doesn’t record until the next business day, and neither does your purchase. This is the single biggest reason simultaneous closings fall apart. Not bad faith, not missing paperwork. A wire that got sent at 11 a.m. instead of 8 a.m.
The Order of Operations, Step by Step
Here’s the sequence your escrow officer is actually managing behind the scenes.
Step 1: Your Buyer’s Funds Arrive
Your buyer’s lender (or your buyer directly, if it’s a cash deal) wires funds to your escrow company. For the funds to be usable same-day, they need to be an actual wire, not a cashier’s check, and they need to land before the county’s morning recording cutoff. Escrow confirms the funds, records your sale, and your transaction is done. This releases your net proceeds.
Step 2: Your Proceeds Move to Your Purchase
Those proceeds move to the escrow company handling your purchase. If it’s the same escrow company handling both sides, this can happen quickly, sometimes within the same morning. If it’s two different companies, expect more lag, because the funds have to be wired between escrow accounts rather than shifted internally.
Step 3: Your Purchase Records and Keys Release
Your purchase escrow confirms your funds are in hand, verifies the seller’s payoff and any other conditions are met, and records your purchase. Once recording is confirmed by the county, the deal closes and keys can change hands.
Every one of those steps depends on the one before it landing early enough in the day. That’s why using the same escrow company for both your sale and your purchase, when possible, removes one entire layer of wire-to-wire risk.
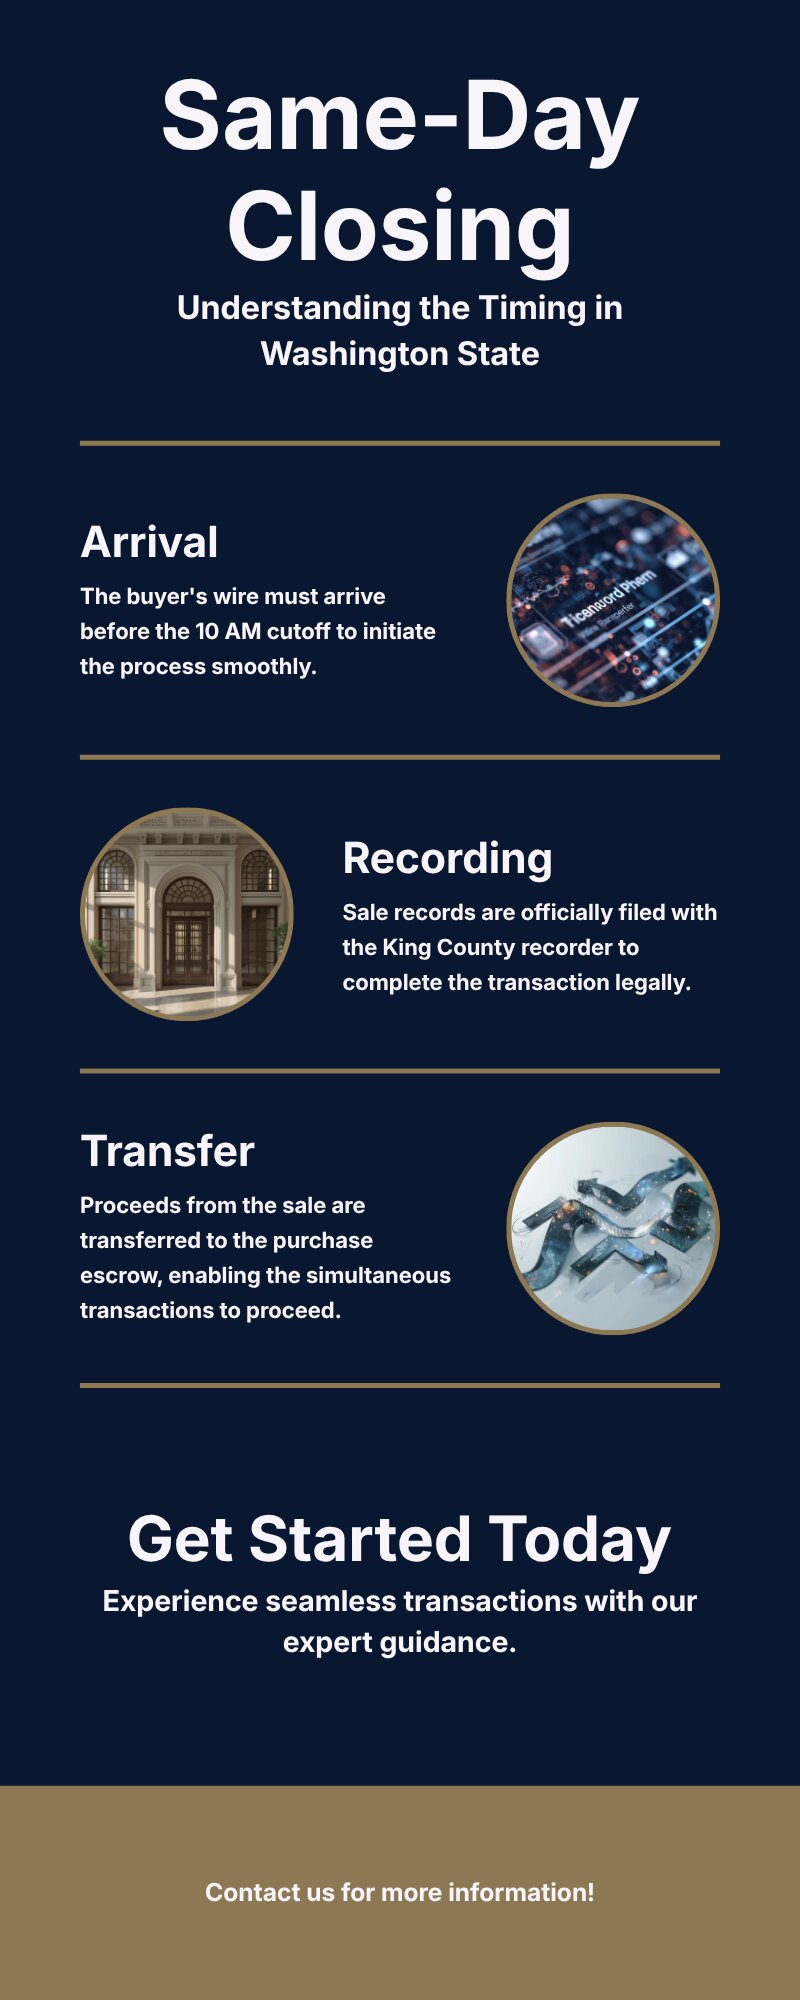
Each step depends on the one before it landing early enough in the day — this is the sequence your escrow officer is managing.
What Can Push Your Simultaneous Closing to the Next Day
A handful of things routinely knock a same-day closing off schedule, and none of them are exotic.
The buyer’s lender wires late. Loan funding often happens later in the process than people expect, especially if the lender isn’t set up to “table fund” (release money without an internal post-signing review). If your buyer’s loan funds at 1 p.m., your sale isn’t recording that morning.
Your outgoing proceeds get held up in transit between escrow companies. Wires generally move same-business-day, but a wire initiated late in the afternoon can land the next morning instead. If your sale records at 11 a.m. and your proceeds don’t clear to your purchase escrow until 2 p.m., your purchase is now racing a clock it can’t win.
A title issue surfaces late. Anything from an unreleased lien to a name discrepancy can stall recording on either side. This is why I tell sellers to get title work started the moment you’re under contract, not the week of closing.
Two different escrow companies aren’t proactively coordinating. When your sale and purchase run through two separate title companies, someone needs to be on the phone connecting the dots early, not exchanging emails the morning of.
The Local Angle: King County Specifics
King County’s market right now makes the timing question more urgent than it might sound. Inventory sits around 3.8 months of supply countywide, median days on market is running about three weeks, and prices are down modestly year over year. That’s a more balanced market than King County has seen in a while, which is good news for move-up sellers: your home is less likely to sit, but you’re also less likely to get a rushed, aggressive closing timeline forced on you by a bidding war. You have more room to negotiate a closing date that actually lines up.
That said, county-level recording infrastructure doesn’t bend for anyone. Whether you’re closing in Renton, Kent, Bellevue, Auburn, or Sammamish, the same 10 a.m.-ish recording cutoff and wire-timing mechanics apply, because it’s the county recorder’s office, not your city, that’s the constraint.
If your purchase is contingent on your sale under NWMLS Form 22B, the same-day closing conversation usually comes up once your sale is under contract and you’re negotiating your own purchase timeline. Your agent should be talking to both escrow companies well before closing week, not the day before.
Getting ahead of title work and lender wire timing early is the difference between a smooth same-day close and a scramble.
What This Means for You as a Seller
If you’re planning to sell and buy on the same day, a few things are worth doing early instead of the week of closing.
Ask your agent to push for the same escrow company on both transactions when it’s realistic. It won’t always be possible, especially if you’re buying from a builder or an estate, but when it is, it removes the biggest point of failure.
Get your title work started as soon as you’re under contract on your sale, not once you’re under contract on your purchase. Title issues are one of the few things in this process you can actually get ahead of.
Confirm your buyer’s loan is set up to table fund, or at least ask your agent to ask. Not every lender does this, and it matters more than most sellers realize.
Build in a one-day buffer if you can. Ask about a short rent-back on your sale side, even a single day, so a wire delay doesn’t leave you standing in a parking lot with a moving truck and nowhere to put it. If a bridge loan or HELOC makes more sense for your situation than timing a same-day close, that’s worth weighing too.
FAQ
Can I really close on selling and buying a home on the same day in Washington?
Yes. It happens regularly, especially when both transactions run through the same escrow company. The key constraint is timing: your sale has to record before your purchase can use those proceeds, and both need to beat the county’s same-day recording cutoff.
What time does my buyer’s wire need to arrive for a same-day closing?
Escrow companies in King County generally need funds in hand by around 10 a.m. to guarantee same-day recording. Earlier is always safer. A wire sent at 9 a.m. is far more reliable than one sent at 9:45.
What happens if my sale doesn’t close in time to fund my purchase?
Your purchase closing slides, usually to the next business day. This is why a short rent-back or a one-day cushion in your purchase contract can save you from a stressful scramble.
Do I need to use the same escrow company for both transactions?
No, but it helps. Using one escrow company for both sides means your proceeds move internally instead of via a wire between two different companies, which cuts out one entire step where things can go wrong.
Is a simultaneous closing the same thing as a double escrow?
No, and this distinction matters. A double escrow (or back-to-back closing) usually refers to an investor reselling a property the same day they buy it, a different transaction type with its own lending and title complications. A simultaneous closing, in the sense most sellers mean it, is simply your own home sale and your own home purchase recording on the same day. You’re not reselling anything, you’re using your proceeds to buy your next home.
What if my purchase depends on selling my current home first?
That’s a home sale contingency, typically documented on NWMLS Form 22B. It’s a related but separate topic from same-day closing mechanics. If you want the deeper dive on how contingent offers work, read the full contingent offer guide alongside this one.
Your guide to life outside Seattle.
253-350-0045 ·
greg@livingoutsideseattle.com ·
www.livingoutsideseattle.com
