

 Facebook
 X
 Pinterest
 Copy Link
September was supposed to be a quiet, steady month for buyers. Then mortgage rates jumped almost three quarters of a point in four weeks. If you were house hunting in King County, your budget changed while you were looking. If you are thinking about selling, your pool of buyers just got smaller.
Here is where rates are now, why they moved, and what it means for you on each side of the deal.
How High Are Mortgage Rates Right Now?
Mortgage News Daily tracks rates every business day. Its 30-year fixed average closed September at 7.60%. That is the highest reading since November 2023. In the past year, the same rate has been as low as 5.99%.
| Loan Type | Rate on Sept. 30, 2026 |
|---|---|
| 30-year fixed | 7.60% (6.89% on Sept. 1) |
| 15-year fixed | 7.22% |
| 30-year jumbo | 7.66% |
| 30-year FHA | 7.25% |
Source: Mortgage News Daily daily rate index. Rates change daily and depend on your credit, down payment, and points.
You may see a lower number in the news. Freddie Mac’s weekly survey showed 7.03% for the week of September 24. Freddie Mac averages a full week and includes loans with points paid up front, so it runs behind the daily index when rates move fast. Both tell the same story. Rates are above 7% and climbing.
Why Did Mortgage Rates Jump in September?
Mortgage rates follow the bond market, not the Fed directly. In September, bond investors started pricing in a tougher road ahead. Mortgage News Daily described it as “a fairly rapid reassessment of the outlooks for Fed policy, inflation, and the supply/demand equation for government debt.”
In plain terms, three things pushed rates up. Inflation has not cooled the way people hoped. The economy keeps running strong. And the government keeps borrowing heavily, which means more bonds for investors to absorb. Tension with Iran and higher fuel prices added pressure early in the month. Even when oil prices dropped late in September, rates kept rising. Matthew Graham of Mortgage News Daily said the increase “cannot be explained by oil prices alone.”
Some of the late-month jump may have come from end-of-quarter trading. That could ease in October. But Mortgage News Daily was clear that a new month does not mean an automatic drop. Real relief likely needs some mix of a calmer situation with Iran, softer economic data, and inflation that falls and stays down. NAR chief economist Lawrence Yun has told buyers to expect 7% as “the new normal” for now.
What 7.6% Mortgage Rates Mean for King County Buyers
Let’s put real numbers on it. King County’s median single-family sale price is $950,000. With 20% down, that is a $760,000 loan.
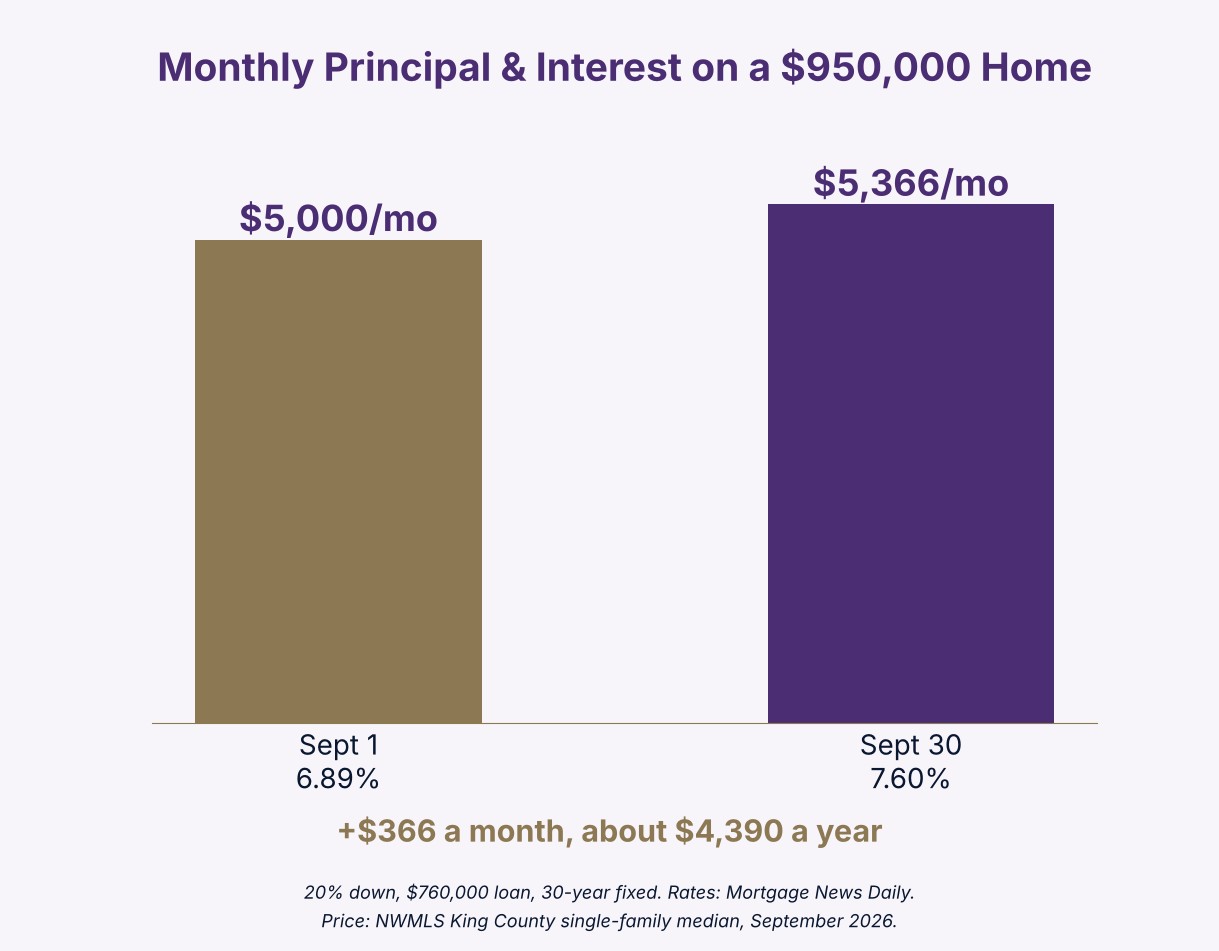
Principal and interest only. Taxes, insurance, and HOA dues are extra.
| 20% Down | At 6.89% | At 7.60% | Change |
|---|---|---|---|
| Median single-family home, $950,000 | $5,000/mo | $5,366/mo | +$366/mo |
| Median condo, $515,000 | $2,711/mo | $2,909/mo | +$198/mo |
Source: NWMLS King County median sale prices, September 2026. Rates from Mortgage News Daily. Principal and interest only.
That is about $4,390 more a year on the median single-family home. Here is another way to see it. The payment that bought a $950,000 home on September 1 now buys a home closer to $885,000. That is roughly $65,000 of buying power gone in one month.
Buyers across the country are feeling it. Fortune reported that mortgage applications were down 19% from a year ago in late September, and pending home sales hit their lowest level in nearly three years. Lisa Sturtevant, chief economist at Bright MLS, said higher rates may push buyers to “compromise on location or square footage, or pause their search altogether.”
Now the other side. Fewer buyers means less competition for you. Redfin found sellers outnumbered buyers by nearly 58% nationally in August, the widest gap in its records going back to 2013. Newsweek put it simply. Buyers who still qualify can now negotiate on price, ask for repairs, ask for help with closing costs, and walk away more easily.
Here is what I am telling buyers right now. Get a fresh pre-approval at today’s rate, because your old letter is probably too high. Shop at least three lenders. NAR noted that rate quotes between lenders can differ by more than half a point, and that is real money every month. Ask the seller for a credit toward a rate buydown instead of just a lower price. A credit that lowers your rate often saves you more per month than the same dollars off the price. My plain-English guide to mortgage rate buydowns walks through how that works. And buy a payment you can live with today. You may be able to refinance later, but don’t count on it when you set your budget.
What Higher Mortgage Rates Mean for King County Sellers
When rates jump, some of the buyers who could afford your home last month can’t anymore. That is the hard truth for sellers this fall. Jake Krimmel, senior economist at Realtor.com, said sellers now face a choice between “slashing prices or delisting their home altogether.”
I don’t think it has to be that stark in King County. Our single-family market has about 4.2 months of supply. That is close to a balanced market, not a buyer’s market yet. But the buyers who are left are more careful. They have more time and more choices.
Concessions are the first place you see it. About 24% of recent King County sales included a seller concession, per NWMLS. Nationally, Fortune reported that close to 45% of sales included concessions, the highest share since 2020. As rates climb, I expect King County’s number to keep moving up.
So what should a seller do? Price it right from the start. Benjamin Schieken of Fincast said sellers are now “pricing homes lower from the start, hoping to attract more buyers.” That beats chasing the market down with price cuts while your days on market add up. Think about offering a rate buydown credit instead of a price cut. To a buyer watching payments, a lower rate can matter more than a lower price. And get the home ready before it hits the market. In a slower market, buyers skip homes that need work.
If you are selling to buy again, remember that your next loan costs more too. If you have a low-rate mortgage today, run the numbers on both sides of the move before you list. Sometimes the move still makes sense. Sometimes waiting does. Either way, you want to know before the sign goes up.
What Changes in the King County Market After Labor Day
Even before rates jumped, fall was already shifting the market. The number of buyers out looking drops after Labor Day as families settle into school and vacation season ends. That doesn’t mean prices crash. What changes is competition per listing, not the price level.
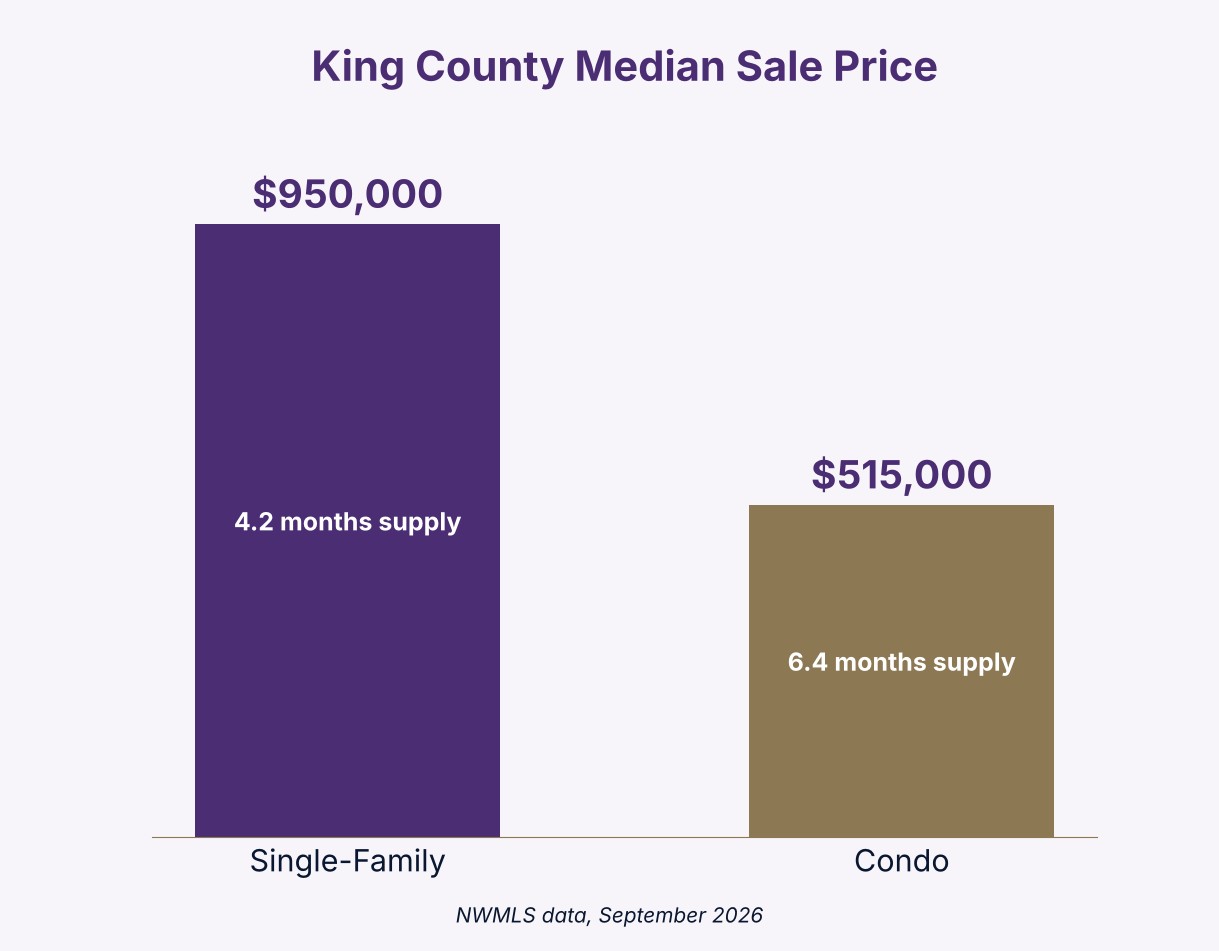
King County’s median sale price, single-family versus condo. Source: NWMLS, September 2026.
King County’s single-family median is $950,000, with condos at $515,000. Single-family homes have about 4.2 months of supply, which is close to balanced. Condos have about 6.4 months, which leans toward buyers. If you are shopping for a condo, you likely have the most room to negotiate right now.
A home still for sale in October or November has usually been sitting since summer. That seller is often more open to talking about price, repairs, or timing than someone who listed in May. Higher rates make that even more true this year.
Where Higher Rates Hit Hardest in King County
Rate jumps don’t land the same everywhere. South King County cities like Kent, Auburn, and Federal Way tend to hold their pace better into fall. Prices are lower there, so a rate jump adds fewer dollars to the payment. On the Eastside, higher prices mean bigger loans. Many buyers there use jumbo loans, which sat at 7.66% at the end of September. That makes the buyer pool smaller and more sensitive to every move in rates.
If you are weighing specific cities, my East and South King County market update tracks city-by-city numbers on an ongoing basis.
Should You Wait for Mortgage Rates to Come Down?
Nobody knows where rates go next. They could ease in October if the end-of-quarter pressure fades. They could also keep climbing if inflation stays stubborn. Waiting is a bet, not a plan.
For buyers, the real question is what waiting costs you. If rates drop next spring, more buyers come back, and so do bidding wars. The leverage you have right now may be gone. I cover this trade-off in my guide to the cost of waiting to buy a home in King County.
For sellers, waiting for spring can make sense if you don’t have to move. Just know that spring brings more competing listings too. If you do need to sell this fall, price for the market we have, not the one we had in June.
Frequently Asked Questions
What are mortgage rates right now in King County?
Mortgage rates are national, so King County buyers see the same averages as everyone else. On September 30, 2026, Mortgage News Daily’s 30-year fixed average was 7.60%. The 15-year fixed was 7.22%, jumbo was 7.66%, and FHA was 7.25%. Your own rate depends on credit, down payment, and points.
How much does a 7.6% mortgage rate add to my payment?
On King County’s $950,000 median single-family home with 20% down, principal and interest rose from about $5,000 a month at 6.89% to about $5,366 at 7.60%. That is roughly $366 more a month. On the $515,000 median condo, it is about $198 more.
Is fall 2026 a good time to buy a home in King County?
For buyers who are pre-approved at today’s rates, it can be. Higher rates have thinned out the competition, and sellers are more open to price cuts, repairs, and closing-cost credits. About 24% of recent King County sales included a seller concession. The trade-off is a higher monthly payment.
Should I sell my King County home now or wait for rates to drop?
If you need to move, you can still sell this fall. Price it right from day one and be ready to offer a concession or rate buydown. If you don’t need to move, waiting for spring is an option. Spring usually brings more buyers, but also more competing listings, and there is no promise rates will be lower.
Will mortgage rates go down soon?
No one can say for sure. Mortgage News Daily said real relief likely needs inflation to fall and stay down, softer economic data, and calmer world events. NAR’s chief economist has said to expect 7% as the new normal for now. Plan your budget around today’s rate, not a hoped-for one.
Your guide to life outside Seattle.
253-350-0045 · greg@livingoutsideseattle.com · www.livingoutsideseattle.com
Gregory Dorrell is a licensed real estate broker (WA License #111862) with Coldwell Banker Danforth. Market data from NWMLS, September 2026. Mortgage rates from the Mortgage News Daily daily index, September 1 and September 30, 2026, and Freddie Mac’s Primary Mortgage Market Survey, week of September 24, 2026. National figures as reported by Fortune, Newsweek, Redfin, Realtor.com, Bright MLS, and NAR in September 2026. Payment examples are principal and interest only. This post is provided for informational purposes and does not constitute financial advice.
