

 Facebook
 X
 Pinterest
 Copy Link
If you’re selling your current home and buying your next one, a simultaneous closing in Washington State is one of the best ways to avoid two moves, a bridge loan, or a rent-back agreement. It also depends on a chain of deadlines most people never think about until they’re staring at a wire cutoff time on closing morning.
I work with move-up sellers across King County who want to time this right. The mechanics aren’t complicated once you understand the order of operations. But the sequence matters, and one missed cutoff can push your move-in to the next day.
Why a Simultaneous Closing in Washington State Is Hard to Pull Off
Washington uses escrow closings, not table closings. Nobody sits around a conference table exchanging keys and checks. Instead, a neutral escrow company holds everyone’s documents and money, then records the deed and releases funds once every condition is met. Signing happens days before closing. Closing is when funds move and the county records the transfer.
That separation is what makes a same-day sale-and-purchase possible, and also what makes it fragile. Your sale has to fully fund and record before your purchase can use those proceeds. If your sale slips to the afternoon, your purchase slips too, or it doesn’t happen that day at all.
King County’s recording cutoff is typically 10 a.m. for same-day recording. If your buyer’s wire hasn’t hit escrow by then, your sale doesn’t record until the next business day, and neither does your purchase. This is the single biggest reason simultaneous closings fall apart. Not bad faith, not missing paperwork. A wire that got sent at 11 a.m. instead of 8 a.m.
The Order of Operations, Step by Step
Here’s the sequence your escrow officer is actually managing behind the scenes.
Step 1: Your Buyer’s Funds Arrive
Your buyer’s lender (or your buyer directly, if it’s a cash deal) wires funds to your escrow company. For the funds to be usable same-day, they need to be an actual wire, not a cashier’s check, and they need to land before the county’s morning recording cutoff. Escrow confirms the funds, records your sale, and your transaction is done. This releases your net proceeds.
Step 2: Your Proceeds Move to Your Purchase
Those proceeds move to the escrow company handling your purchase. If it’s the same escrow company handling both sides, this can happen quickly, sometimes within the same morning. If it’s two different companies, expect more lag, because the funds have to be wired between escrow accounts rather than shifted internally.
Step 3: Your Purchase Records and Keys Release
Your purchase escrow confirms your funds are in hand, verifies the seller’s payoff and any other conditions are met, and records your purchase. Once recording is confirmed by the county, the deal closes and keys can change hands.
Every one of those steps depends on the one before it landing early enough in the day. That’s why using the same escrow company for both your sale and your purchase, when possible, removes one entire layer of wire-to-wire risk.
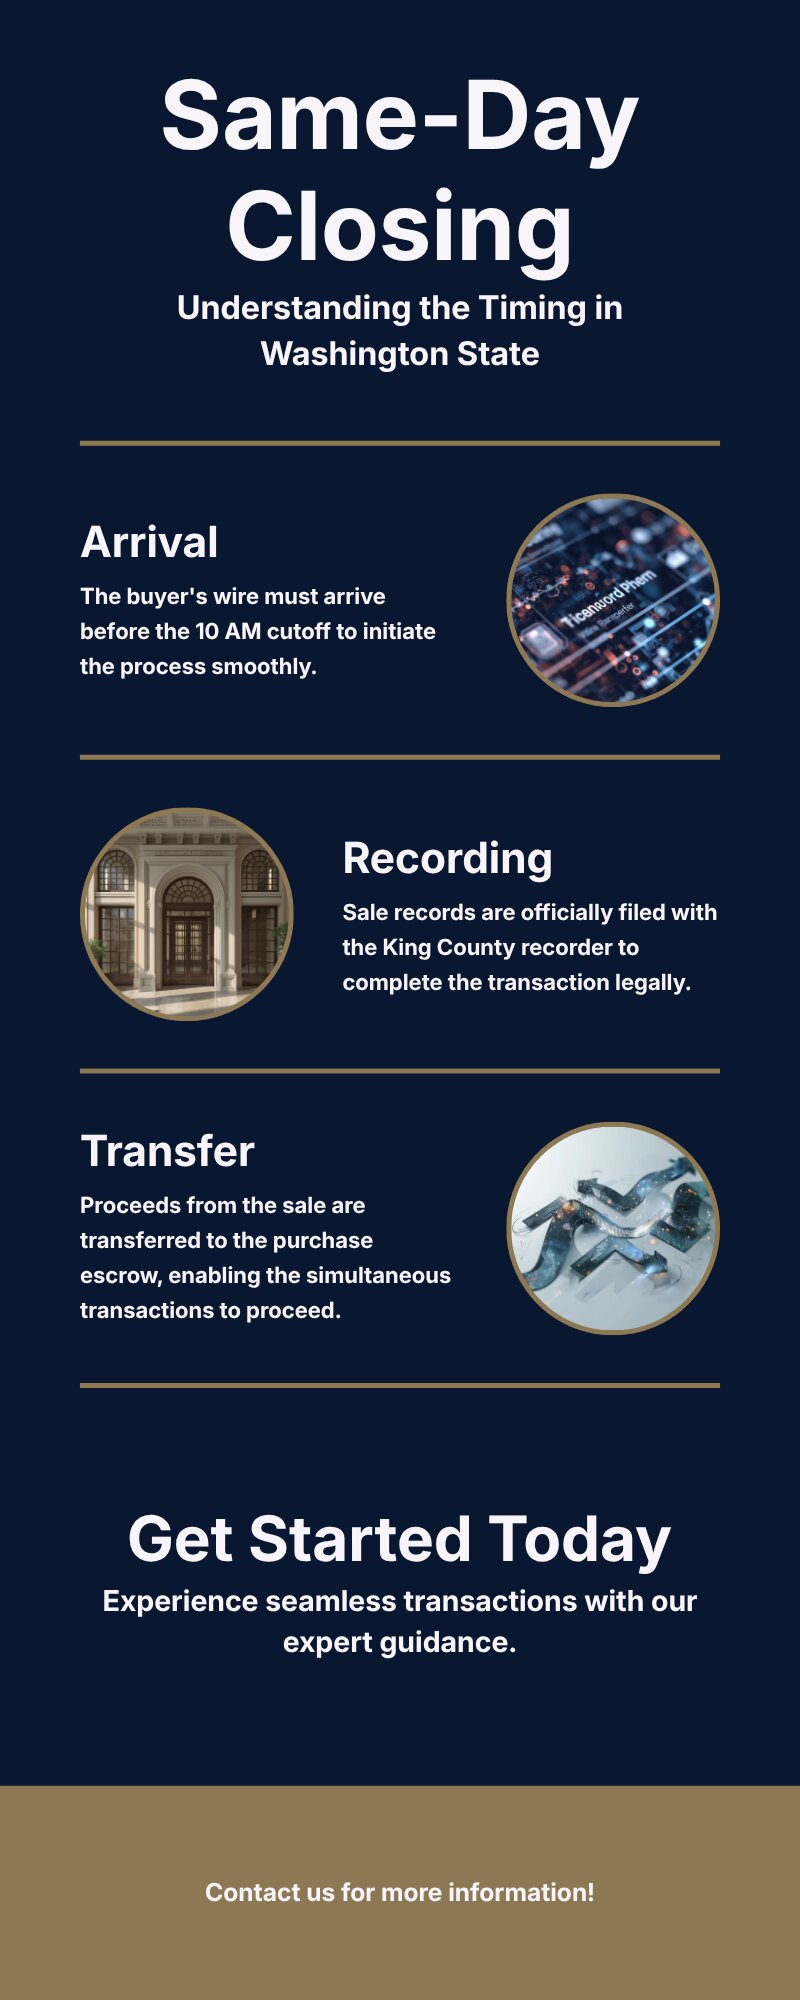
Each step depends on the one before it landing early enough in the day — this is the sequence your escrow officer is managing.
What Can Push Your Simultaneous Closing to the Next Day
A handful of things routinely knock a same-day closing off schedule, and none of them are exotic.
The buyer’s lender wires late. Loan funding often happens later in the process than people expect, especially if the lender isn’t set up to “table fund” (release money without an internal post-signing review). If your buyer’s loan funds at 1 p.m., your sale isn’t recording that morning.
Your outgoing proceeds get held up in transit between escrow companies. Wires generally move same-business-day, but a wire initiated late in the afternoon can land the next morning instead. If your sale records at 11 a.m. and your proceeds don’t clear to your purchase escrow until 2 p.m., your purchase is now racing a clock it can’t win.
A title issue surfaces late. Anything from an unreleased lien to a name discrepancy can stall recording on either side. This is why I tell sellers to get title work started the moment you’re under contract, not the week of closing.
Two different escrow companies aren’t proactively coordinating. When your sale and purchase run through two separate title companies, someone needs to be on the phone connecting the dots early, not exchanging emails the morning of.
The Local Angle: King County Specifics
King County’s market right now makes the timing question more urgent than it might sound. Inventory sits around 3.8 months of supply countywide, median days on market is running about three weeks, and prices are down modestly year over year. That’s a more balanced market than King County has seen in a while, which is good news for move-up sellers: your home is less likely to sit, but you’re also less likely to get a rushed, aggressive closing timeline forced on you by a bidding war. You have more room to negotiate a closing date that actually lines up.
That said, county-level recording infrastructure doesn’t bend for anyone. Whether you’re closing in Renton, Kent, Bellevue, Auburn, or Sammamish, the same 10 a.m.-ish recording cutoff and wire-timing mechanics apply, because it’s the county recorder’s office, not your city, that’s the constraint.
If your purchase is contingent on your sale under NWMLS Form 22B, the same-day closing conversation usually comes up once your sale is under contract and you’re negotiating your own purchase timeline. Your agent should be talking to both escrow companies well before closing week, not the day before.
Getting ahead of title work and lender wire timing early is the difference between a smooth same-day close and a scramble.
What This Means for You as a Seller
If you’re planning to sell and buy on the same day, a few things are worth doing early instead of the week of closing.
Ask your agent to push for the same escrow company on both transactions when it’s realistic. It won’t always be possible, especially if you’re buying from a builder or an estate, but when it is, it removes the biggest point of failure.
Get your title work started as soon as you’re under contract on your sale, not once you’re under contract on your purchase. Title issues are one of the few things in this process you can actually get ahead of.
Confirm your buyer’s loan is set up to table fund, or at least ask your agent to ask. Not every lender does this, and it matters more than most sellers realize.
Build in a one-day buffer if you can. Ask about a short rent-back on your sale side, even a single day, so a wire delay doesn’t leave you standing in a parking lot with a moving truck and nowhere to put it. If a bridge loan or HELOC makes more sense for your situation than timing a same-day close, that’s worth weighing too.
FAQ
Can I really close on selling and buying a home on the same day in Washington?
Yes. It happens regularly, especially when both transactions run through the same escrow company. The key constraint is timing: your sale has to record before your purchase can use those proceeds, and both need to beat the county’s same-day recording cutoff.
What time does my buyer’s wire need to arrive for a same-day closing?
Escrow companies in King County generally need funds in hand by around 10 a.m. to guarantee same-day recording. Earlier is always safer. A wire sent at 9 a.m. is far more reliable than one sent at 9:45.
What happens if my sale doesn’t close in time to fund my purchase?
Your purchase closing slides, usually to the next business day. This is why a short rent-back or a one-day cushion in your purchase contract can save you from a stressful scramble.
Do I need to use the same escrow company for both transactions?
No, but it helps. Using one escrow company for both sides means your proceeds move internally instead of via a wire between two different companies, which cuts out one entire step where things can go wrong.
Is a simultaneous closing the same thing as a double escrow?
No, and this distinction matters. A double escrow (or back-to-back closing) usually refers to an investor reselling a property the same day they buy it, a different transaction type with its own lending and title complications. A simultaneous closing, in the sense most sellers mean it, is simply your own home sale and your own home purchase recording on the same day. You’re not reselling anything, you’re using your proceeds to buy your next home.
What if my purchase depends on selling my current home first?
That’s a home sale contingency, typically documented on NWMLS Form 22B. It’s a related but separate topic from same-day closing mechanics. If you want the deeper dive on how contingent offers work, read the full contingent offer guide alongside this one.
Your guide to life outside Seattle.
253-350-0045 ·
greg@livingoutsideseattle.com ·
www.livingoutsideseattle.com
