

 Facebook
 X
 Pinterest
 Copy Link
What Happened to Mortgage Rates This Month
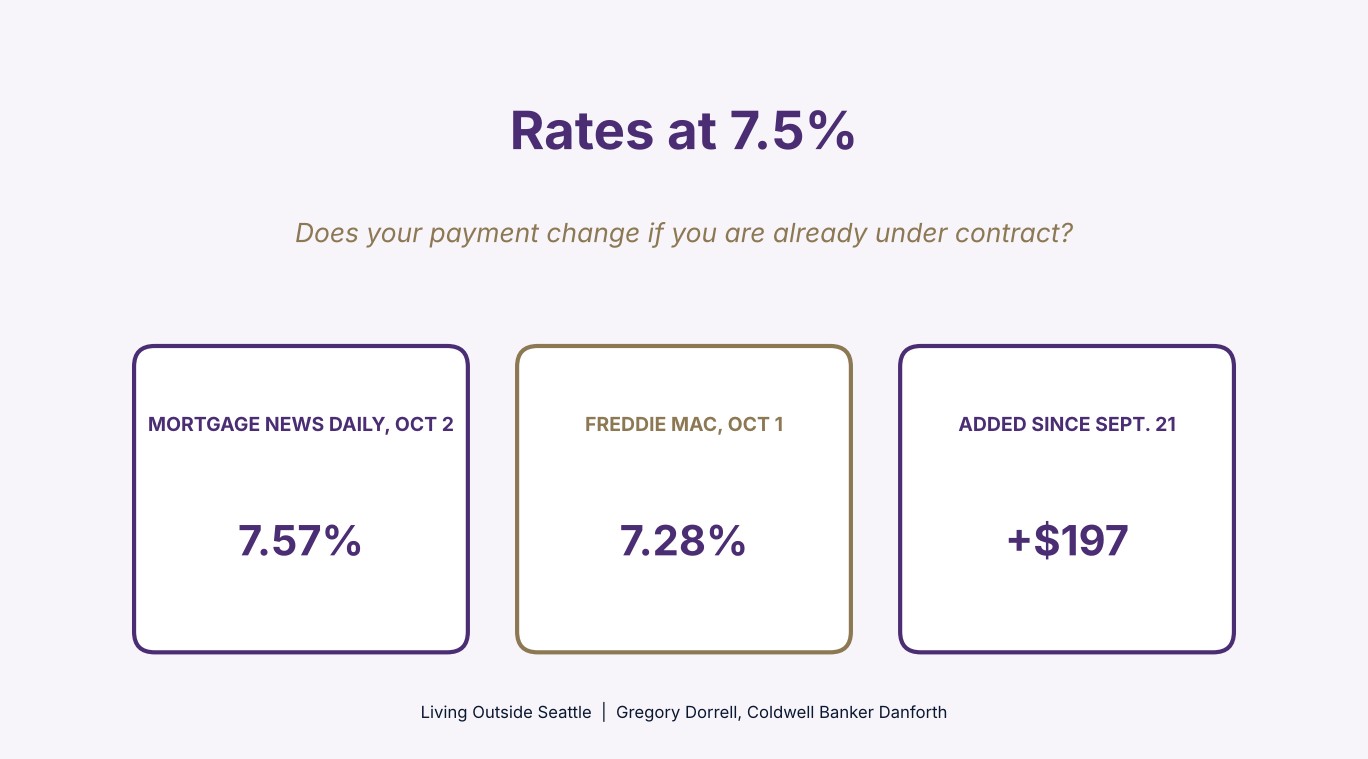
Rates moved fast. Mortgage News Daily tracks a 30-year fixed rate every day. It closed at 7.57% on October 2, after peaking at 7.60% on September 30. On September 21 it was 7.19%. That is a jump of about 0.4 points in under two weeks.
Freddie Mac’s weekly survey says 7.28% for the week of October 1. That number runs behind because it is a weekly average. The Fed also raised its rate on September 16, the first hike since 2023. So the rate buyers are seeing on quotes this week is closer to 7.5%. I broke down the bigger picture in my guide on what 7%+ mortgage rates mean for King County buyers and sellers.
Does My Payment Change If I Am Already Under Contract?
Not if your rate is locked. A rate lock is a promise from your lender to hold a specific rate for a set number of days. Lock periods are often 30, 45, or 60 days, and longer locks can cost more. Ask your lender what yours is. My rate lock guide for Washington buyers explains how locks work in more detail.
In my experience, buyers usually lock around the time the offer is made. That means a rate jump after the offer does not touch them. I want to be clear about this because a lot of the news makes it sound like every buyer is getting hit. They are not.
Who Is Exposed to the Rate Jump
The jump hits buyers in four spots:
- Buyers who are under contract but have not locked. Their rate floats until they lock, so today’s quote is the one that counts.
- Buyers whose lock runs out before closing. If closing slips past the lock date, an extension can cost money.
- Buyers who have not made an offer yet. Every quote they get now reflects the higher rate.
- Buyers who switch lenders or loan types after locking. A new loan usually means a new rate.
What the Jump Costs on a $950,000 Home
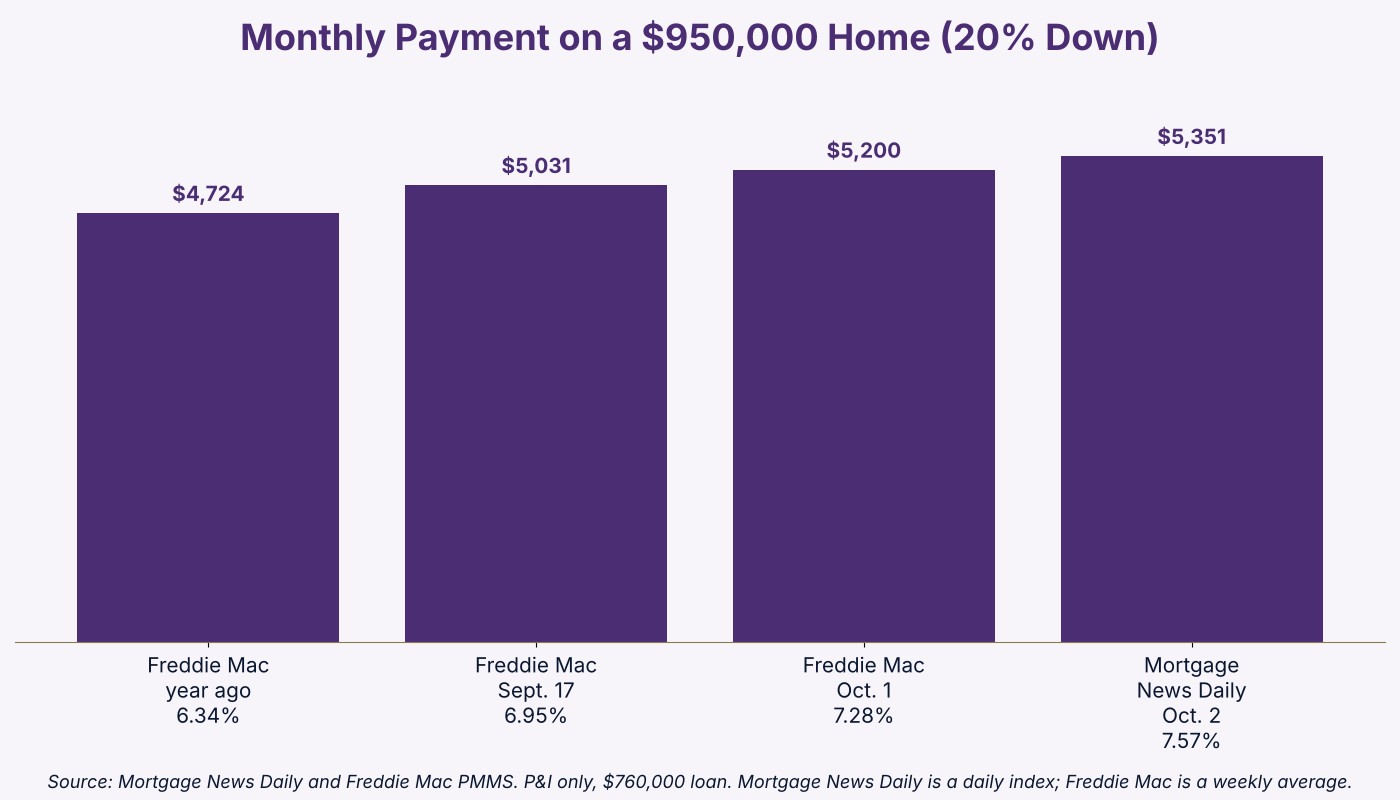
I ran the numbers on a $950,000 home with 20% down. That is a $760,000 loan, which is close to the county single-family median of $945,000. These figures are principal and interest only. Taxes and insurance come on top.
| Date and source | Rate | Monthly payment |
|---|---|---|
| Freddie Mac, a year ago | 6.34% | $4,724 |
| Freddie Mac, Sept. 17 | 6.95% | $5,031 |
| Mortgage News Daily, Sept. 21 | 7.19% | $5,154 |
| Freddie Mac, Oct. 1 | 7.28% | $5,200 |
| Mortgage News Daily, Oct. 2 | 7.57% | $5,351 |
Source: Mortgage News Daily and Freddie Mac PMMS. Principal and interest only, 30-year fixed, $760,000 loan.
Look at the two daily index rows. From September 21 to October 2, the payment rose by about $197 a month. Compared with a year ago on Freddie Mac’s weekly numbers, today’s payment is about $476 a month higher. Those are real dollars, and they are why this matters for anyone who has not locked.
What To Do This Week, Based on Where You Are
You are under contract and locked
Do nothing about the rate. Check two dates instead: your lock expiration and your closing date. If closing could slip, ask your lender today what an extension costs.
You are under contract and not locked
Call your lender today. Ask what it costs to lock now and for how long. Waiting for rates to fall is a guess, and the Fed just raised its rate, not cut it.
You are still shopping
Set your budget at today’s rate, not last month’s. Get a written quote. Then look at what the seller can do for you. About 26% of King County sales in the latest data included seller concessions, which can pay for part of a rate buydown. My guide to mortgage rate buydowns shows how that works.
Frequently Asked Questions
Does my payment change if rates go up after my offer is accepted?
Not if you have locked your rate. A lock holds your rate for a set number of days, often 30 to 60. If you have not locked, your rate can still move, so ask your lender when to lock.
When should I lock my mortgage rate?
It depends on your lender and your timeline. Many buyers lock around the time the offer is made or accepted. Ask your lender what lock periods they offer and what a longer lock costs.
What happens if my rate lock expires before closing?
Your lender may charge a fee to extend the lock, or you may get the current market rate. Ask about extension costs before you need one.
Should I wait for rates to drop before buying?
Nobody can promise that. The Fed raised its rate in September, and rates have gone up, not down. If you find the right home, a payment you can handle today beats guessing. My cost of waiting guide walks through the math.
Your guide to life outside Seattle.
253-350-0045 · greg@livingoutsideseattle.com · www.livingoutsideseattle.com
Rates from Mortgage News Daily (Oct. 2, 2026) and Freddie Mac PMMS (week of Oct. 1, 2026). Market data from NWMLS, week of October 5, 2026. Gregory Dorrell is a licensed real estate broker (WA License #111862) with Coldwell Banker Danforth. This post is provided for informational purposes and does not constitute financial or investment advice.
