

 Facebook
 X
 Pinterest
 Copy Link
A plain-English look at the three kinds of lender letters, which one a King County seller will take seriously, and how to get the strong one before you tour a single home.
Most buyers think a pre-approval letter is a pre-approval letter. It is not. Lenders hand out three different documents that sound almost the same, and sellers and their agents rank them very differently. I see these letters from both sides of the table across Renton, Kent, and Auburn, and I can usually tell in about ten seconds which offers are real.
Here is why it matters right now. With mortgage rates above 7% this fall, sellers are watching for buyers who can actually close. A weak letter will not lose you the house on its own. But when two offers are close, the buyer with the stronger letter wins more often than not.
Pre-Qualification: A Conversation, Not a Commitment
A pre-qualification is the lightest version. You tell a lender, or an online tool, your income, your debts, and your savings. They run the numbers and give you a range. Sometimes there is a soft credit check. Often there is not.
Nobody verifies anything. Your pay stubs stay in the drawer. That is why it takes ten minutes.
So what? A pre-qualification is useful for one thing: getting a rough price range before you start the real process. It tells you whether $550,000 or $750,000 is even in the neighborhood. It does not tell a seller anything they can rely on, because nothing in it has been checked.
Pre-Approval: The Letter Most Offers Are Written With
A true pre-approval means you applied. The lender pulls your credit and collects documents: recent pay stubs, W-2s or tax returns, and bank statements. A loan officer reviews them and issues a letter saying you are approved up to a stated amount, subject to conditions.
That last phrase matters. A standard pre-approval is a conditional commitment. The lender has looked at your file, but an underwriter has not yet gone line by line through it. Final approval still depends on the appraisal, the title work, and your finances staying the same until closing.
So what? This is the letter sellers expect to see attached to an offer in King County. It shows you are serious, and it shows a real person at a real lender looked at your numbers. For most buyers, this is the right letter to have in hand before the first showing.
Underwritten Pre-Approval: The Strongest Letter You Can Carry
Some lenders will take your pre-approval one step further. Your full file goes to an underwriter before you ever find a house. The underwriter reviews income, assets, debts, and credit, and issues a conditional approval that is mostly done. What is left is the property itself: the appraisal, title, and insurance.
This version goes by different names depending on the lender, including pre-underwritten, fully underwritten, or verified approval. Ask your lender what they call theirs and what has actually been reviewed.
So what? Fewer unknowns means a faster, calmer close. Sellers like that, especially when they are choosing between offers with similar prices. If a seller is also buying a home, a smoother closing can matter as much as a few thousand dollars.
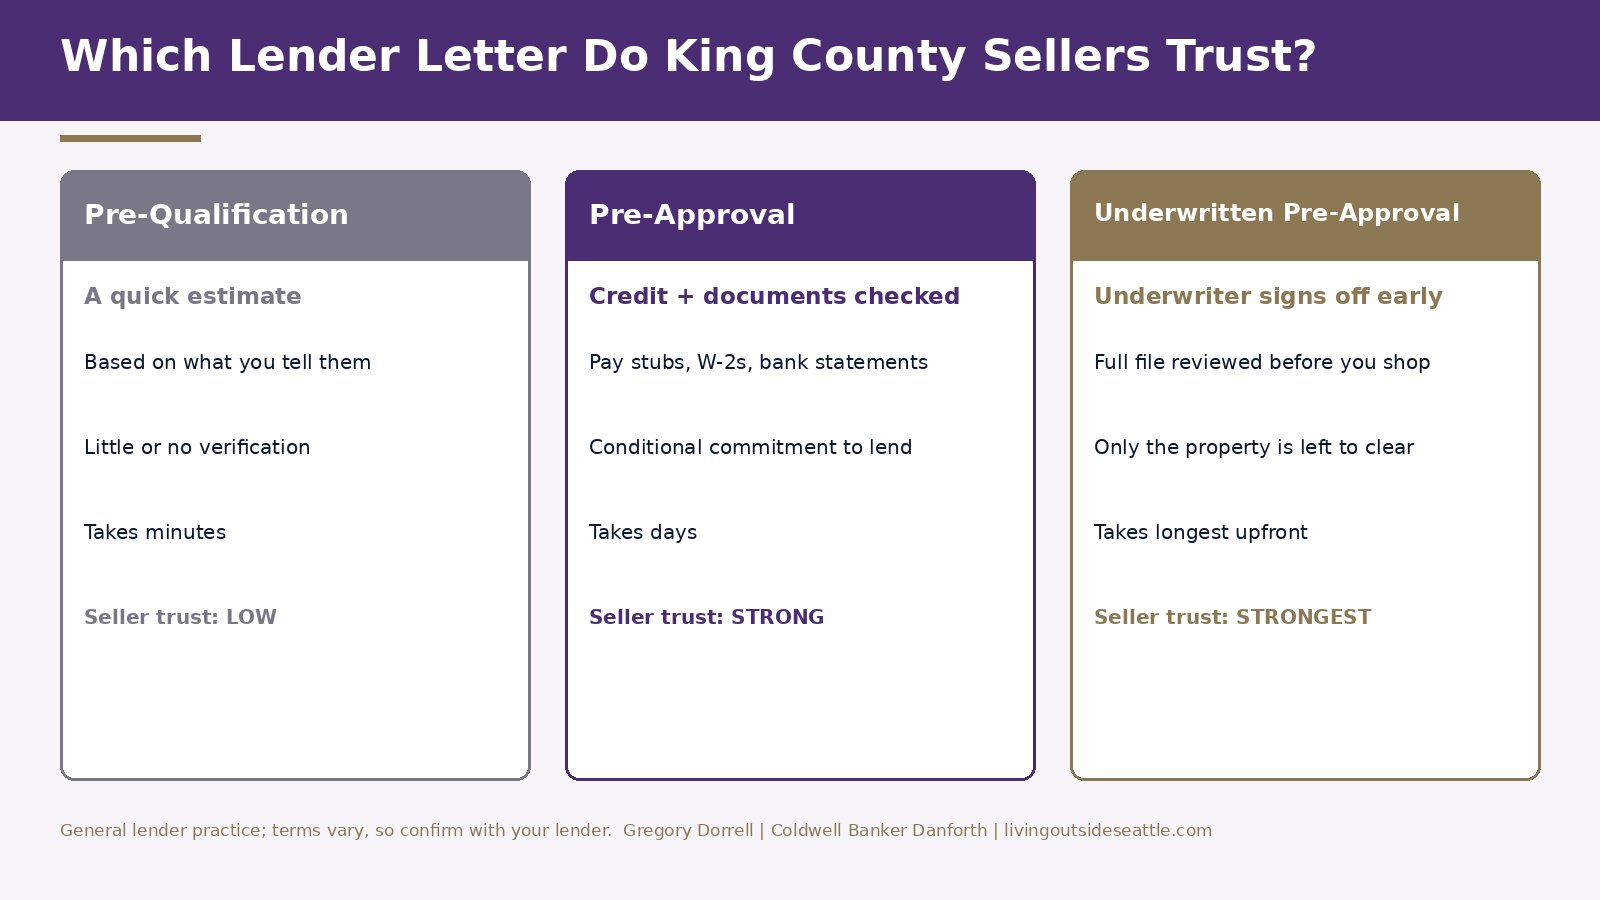
What each lender letter verifies, and how much weight King County sellers give it.
The Local Angle: What King County Sellers Are Looking For
King County is not one market. A seller in Sammamish and a seller in Kent are reading offers differently, because their buyers and their timelines are different.
Take price. The median single-family home in Kent sold for about $697,725 over the 12 months through August 2026, and in Renton it was about $783,750. Those are single-family medians, not blended with condos. At those prices, a buyer putting 5% down is still borrowing roughly $660,000 to $745,000. Sellers read the dollar figure on your letter closely. Make sure it covers the price you are offering, not the price you hope to pay.
Now timing. In a softer fall market, some sellers are willing to wait a little for the right buyer. But the offers they like best are still the ones that look easy to close. A verified letter makes that case before you say a word.
What Makes a Letter Look Strong to a Seller
Sellers and their agents check a few simple things. First, the letter is on the lender’s letterhead and names the buyer. Second, the approval amount covers your offer price with room to spare. Third, the date is recent. Letters commonly expire after 60 to 90 days, so ask your lender how long yours is good for. Fourth, the loan type matches the offer: if you are using an FHA loan, the letter should say so.
Fifth, and this one gets missed, the lender is someone the listing agent can call. Local lenders with a track record in King County close deals sellers have seen before. An unfamiliar online lender is not disqualifying, but it raises questions. I would rather you answer those questions in advance than during a negotiation.
So what? You do not need a perfect letter. You need one that answers the seller’s questions before they ask.
Get the letter before you need it. Offers move fast once the right home lists.
What This Means for You as a Buyer
If you are two or more months from buying, start with a pre-qualification. It costs nothing and sets your range. Then move on to a real application.
If you are within a few months, get the full pre-approval. Do not wait until you find the house. I have watched buyers lose a weekend gathering documents while another offer went in.
If you expect multiple offers on a home, or you are buying while selling, ask your lender about an underwritten pre-approval. It takes more upfront work, and it may cost you a few extra days. In return, you carry a letter that looks a lot like cash to a seller.
If you want to see how lenders reach the number, my guide on how mortgage qualification works in Washington State walks through income, debt-to-income, credit, and down payment. Once you have a letter and a house, the next question is timing, so read how a mortgage rate lock works in Washington. And for the cash side of an offer, see earnest money in King County and buyer closing costs in King County. If you are weighing a program to lower your rate, rate buydowns are covered here.
Frequently Asked Questions
What is the difference between pre-approval and pre-qualification?
A pre-qualification is an estimate based on information you provide, with little or no verification. A pre-approval means the lender pulled your credit and reviewed documents like pay stubs and bank statements. Sellers rely on pre-approvals. They treat pre-qualifications as a rough guide.
Do King County sellers accept a pre-qualification letter with an offer?
Most listing agents will not treat a pre-qualification as proof of financing. Because nothing has been verified, it carries little weight, especially when other offers include a full pre-approval. Get the pre-approval before you write an offer.
Does a pre-approval hurt my credit score?
A pre-approval usually involves a hard credit inquiry, which can lower your score by a small amount for a short time. Multiple mortgage inquiries within a short window are generally treated as one for scoring purposes. Ask your lender how that works with the scoring model they use.
How long does a pre-approval letter last?
Most letters are good for roughly 60 to 90 days, though it varies by lender. If your search runs longer, ask for an updated letter. Lenders may need fresh pay stubs and bank statements.
Is a pre-approval a guarantee I will get the loan?
No. It is a conditional commitment. Final approval depends on the appraisal, the title work, and your finances staying the same through closing. An underwritten pre-approval removes more of the unknowns, but the property still has to qualify.
Should I get pre-approved with more than one lender?
It is worth comparing at least two or three lenders on rate, fees, and how well they communicate. Doing it within a short span keeps the credit impact small. Pick the lender you trust to answer the phone the day an offer is due.
Get the Letter Before You Need It
A pre-qualification gets you a number. A pre-approval gets you taken seriously. An underwritten pre-approval gets you the benefit of the doubt when offers are close. In King County, the buyers who get the keys are usually the ones who did the boring paperwork first.
Whether you are a first-time buyer in Kent or Auburn, or moving up in Renton, I am happy to walk through the real numbers with you and introduce you to lenders I trust. No pressure, no sales pitch. Reach me at greg@livingoutsideseattle.com or 253-350-0045, or find more guides at www.livingoutsideseattle.com.
Your guide to life outside Seattle.
253-350-0045 ·
greg@livingoutsideseattle.com ·
www.livingoutsideseattle.com
