

 Facebook
 X
 Pinterest
 Copy Link
Rent-Back Agreements: A King County Seller’s Guide
Selling your King County home doesn’t mean you have to be out the same day the buyer gets the keys. A rent-back agreement lets you stay put for a few extra weeks and close the timing gap most sellers dread.
I get this question almost every week from sellers who are stuck on one problem: their house is about to sell, but their next place isn’t ready yet. Maybe the new construction isn’t finished. Maybe the seller they’re buying from won’t move out until October. Maybe they just need three weeks to pack a house their family has lived in for fifteen years without doing it in a panic.
A rent-back agreement solves that. It’s a simple idea with real legal teeth in Washington, and if you’re selling in King County right now, it’s worth understanding before you’re mid-negotiation and trying to learn it on the fly.
What a Rent-Back Agreement Actually Is
Here’s the honest mechanics of it. On closing day, the buyer owns your house. You get your sale proceeds. And then you become the buyer’s tenant, paying them rent to stay in the home you just sold.
That flip in roles surprises a lot of sellers. You’re not delaying the sale. The sale happens on schedule, title transfers, and your equity lands in your account. What changes is who owns the walls around you while you finish your move.
In Washington, this gets formalized with NWMLS Form 65B, Rental Agreement for Seller Occupancy After Closing. It’s a real lease, even if it’s short. It spells out your move-out date, your rent amount, who pays utilities, who’s responsible for damage, and what happens if you don’t leave on time. I always tell sellers: read this form as carefully as you read your purchase agreement. It’s not a formality. It’s the document that protects you if anything about your move goes sideways.
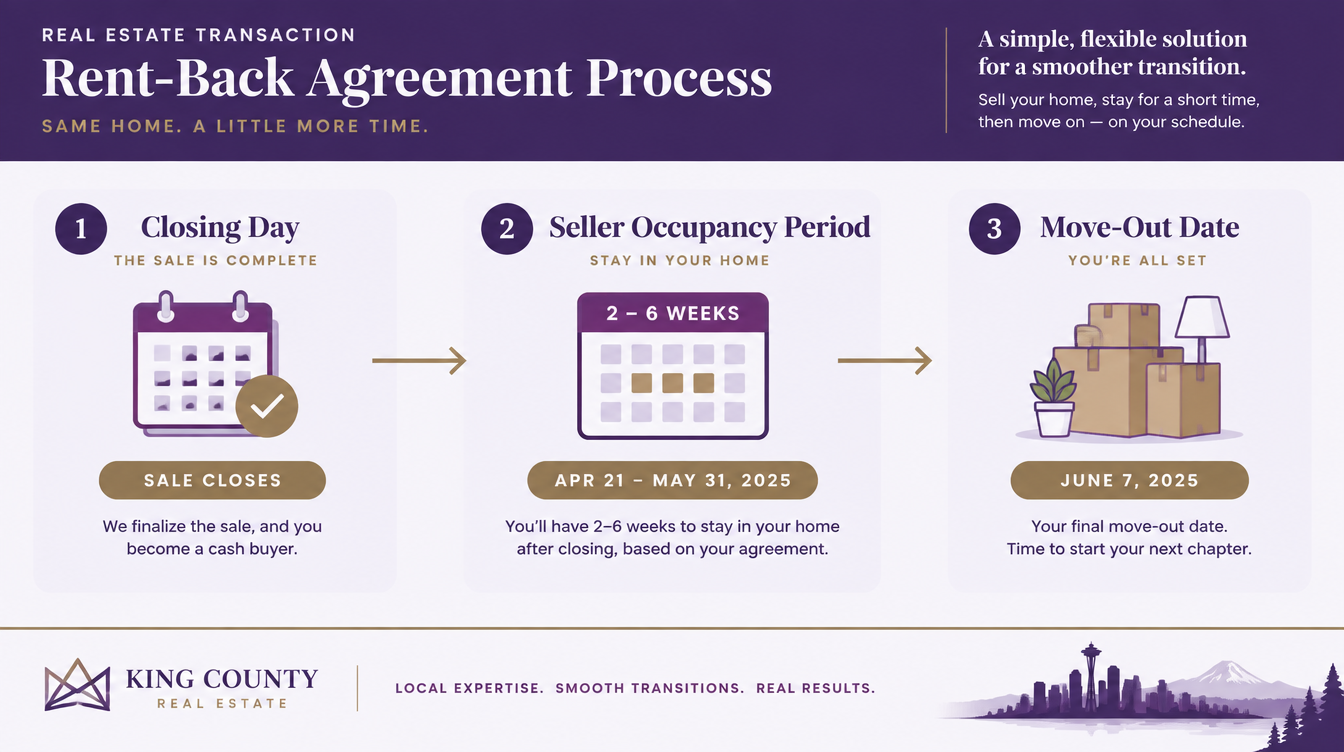
The three-month NWMLS legal cap and the buyer’s 60-day lender deadline are two separate limits. The tighter one wins.
One detail that trips people up: the occupancy period is capped at three months after closing under the standard NWMLS form, and no rent can be collected past that three-month mark. In practice, most rent-backs I see in King County run two to six weeks. Anything longer starts running into a different set of complications, which I’ll get to next.
Why There’s a Hard Time Limit
This isn’t NWMLS being arbitrary. It comes down to how the buyer’s mortgage works.
If your buyer used a conventional, FHA, or VA loan to purchase the home, they almost certainly signed an owner-occupancy agreement with their lender. That document says they intend to move into the property as their primary residence, usually within 60 days of closing. Fannie Mae, Freddie Mac, and FHA all build this requirement into their loan terms.
For you as the seller, that means your buyer has a real deadline of their own, tied to their mortgage, not just their patience. Let them stay past that window without a documented, lender-aware exception, and they’re putting their own loan compliance at risk. That’s not small. It’s the reason most rent-backs in King County stay short. And it’s the reason your agent should be checking your buyer’s loan type before this gets negotiated, not after.
Don’t ask for six weeks when you might only need two. And don’t assume you can extend a rent-back the way you’d extend a normal lease. The three-month legal ceiling and the buyer’s 60-day owner-occupancy clock are two separate limits. The tighter one wins.
What It Actually Costs You
Rent-back agreements aren’t free, and they shouldn’t be. There are two common ways to set the rent number, and I’ve seen both work well depending on the situation.
The first is tying it to the buyer’s daily carrying cost, their principal, interest, taxes, and insurance (PITI), divided by 30. If their new mortgage payment is $3,200 a month, that’s roughly $107 a day. This approach feels fair to buyers because it just covers what owning the home is actually costing them while you’re still in it.
The second is fair market rent, based on what comparable homes in your King County neighborhood are renting for. In tighter rental markets like Renton or Kent, this can run higher than the PITI number. In softer pockets, it can run lower.
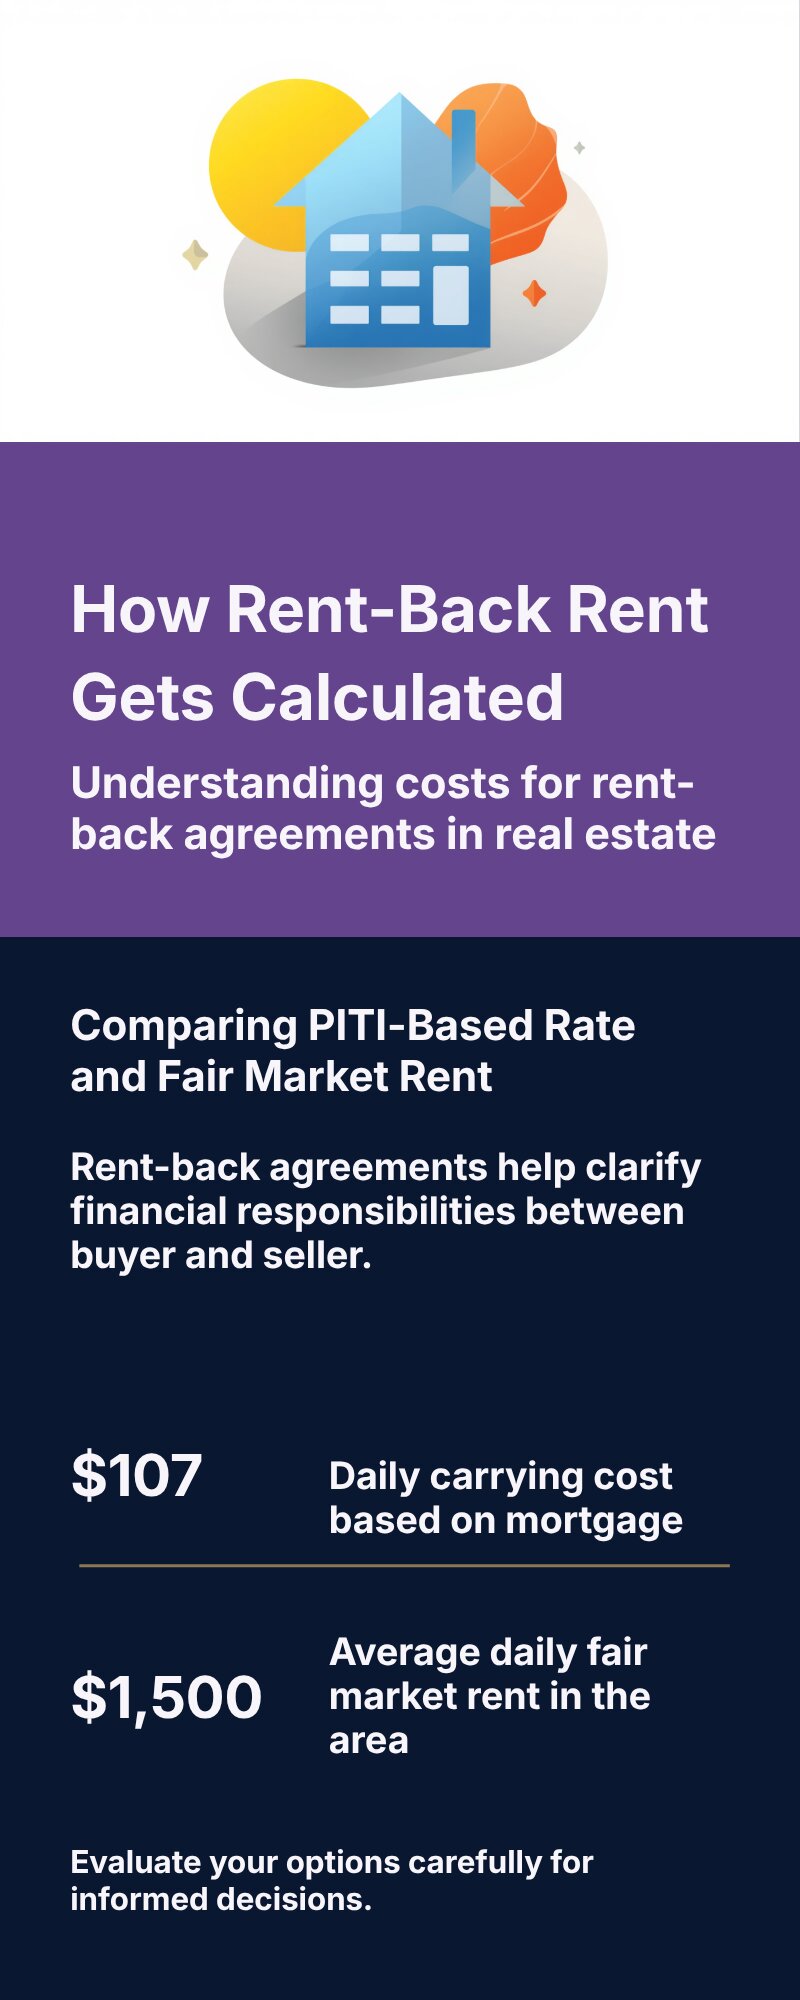
Rent-back rent is usually set one of two ways: the buyer’s daily carrying cost, or fair market rent for the neighborhood.
Either way, expect a security deposit held by the title company, and expect the buyer’s agent to push for a number that at least covers their costs. I generally recommend sellers budget for the higher of the two calculations when they’re planning their move-out cash flow. It’s a rent payment on top of a move you’re already paying for, and it should be part of your closing math from day one, alongside your other costs to sell in Washington State, not a surprise you’re negotiating with movers already in your driveway.
Insurance Is the Part People Forget
This is the piece I see catch people off guard the most. Your homeowners insurance policy ends at closing. Full stop. The buyer’s new policy takes over the property, but it doesn’t automatically cover you as an occupant staying behind.
Sellers staying in the home during a rent-back need their own renter’s insurance in place before closing, not after. This protects your personal belongings, and it gives the buyer an added layer of protection too, since it shows there’s coverage in place if something happens while you’re the one living there. Both sides should confirm this with their insurance carriers before the rent-back period starts, not assume it’s handled.
I bring this up with every seller considering a rent-back. It’s the one detail that’s easy to skip in the excitement of getting your timing solved. Don’t skip it.
The Local Angle: King County Specifics
King County’s market right now makes rent-backs more common than they were a couple years ago, not less. Inventory is up sharply year over year, sitting around 3.9 months of supply countywide as of early September, and prices have softened about 4% from a year ago. That’s still a market that leans toward sellers, but it’s closer to balanced than it’s been in a while.
What that means practically: buyers have more selection and a little more patience right now, which makes them more willing to negotiate a rent-back to win your listing, especially if you’re priced right and your home shows well. I’m seeing this play out across Renton, Kent, and Auburn, where move-up sellers are using rent-backs to bridge the gap while their next purchase closes, rather than scrambling into short-term housing or a storage unit.
On the Eastside, in Bellevue and Sammamish, I’m seeing rent-backs used differently, mostly by sellers who are building or waiting on new construction to finish. Those timelines run longer than a typical closing gap, so the rent-back covers the last stretch, not the whole wait.
Every rent-back should be written into the purchase and sale agreement, with a real move-out date on the calendar.
Every rent-back I negotiate gets written into the purchase and sale agreement itself, never handled as a handshake side deal. That’s what makes it enforceable if something doesn’t go as planned.
What This Means for You as a Seller
If you’re weighing a move-up sale in King County and your timing doesn’t line up cleanly, ask about a rent-back before you assume you’ll need a bridge loan or HELOC, or a short-term rental. It’s often the simplest, cheapest way to close the gap between selling your current home and getting into your next one. For the full playbook on structuring a double move, see my guide on selling and buying a house at the same time in King County.
Talk to your lender’s loan officer about your buyer’s loan type early, before you’re negotiating the rent-back terms. Get your renter’s insurance lined up before closing, not the week of. And put the whole arrangement in writing on NWMLS Form 65B, with a real move-out date and a real rent number, so there’s no ambiguity if your timeline shifts.
FAQ
Is a rent-back agreement legal in Washington State?
Yes. It’s a standard, well-established tool, formalized through NWMLS Form 65B. As long as the agreement stays within its own terms, it’s exempt from the Residential Landlord-Tenant Act, which keeps the process simpler for both sides.
How long can a seller rent back their home after closing in King County?
The NWMLS form caps occupancy at three months after closing, with no rent collected past that point. In practice, most buyers’ loan terms require them to move in within 60 days, so that’s the tighter and more realistic limit for most transactions.
Who pays for utilities during a rent-back period?
This is negotiated in the agreement itself. Some sellers keep utilities in their name and pay directly through the rent-back period; others fold utility costs into the rent number. Either way, it should be spelled out in writing, not assumed.
Does a rent-back affect my mortgage payoff or sale proceeds?
No. The sale closes on schedule and your proceeds are disbursed at closing like any other sale. The rent-back is a separate rental arrangement that happens after you no longer own the home.
What happens if I don’t move out on the agreed date?
This is where the written agreement matters most. Form 65B addresses holdover liability, and if a seller doesn’t vacate on time, the buyer may have to pursue a formal eviction process. It’s rare, but it’s exactly why the terms need to be clear and realistic from the start, not optimistic.
Can I negotiate a rent-back into my offer if I’m buying and selling at the same time?
Yes, and this is one of the most common uses I see. If you’re selling your King County home to buy your next one, a rent-back on the sale side can buy you the days or weeks you need to close on your purchase without double-moving. It pairs naturally with a contingent offer or a bridge loan strategy on the buy side, depending on your equity position.
Your guide to life outside Seattle.
253-350-0045 ·
greg@livingoutsideseattle.com ·
www.livingoutsideseattle.com
Sell and Buy a House at the Same Time in King County
Most people find their next house before they’ve figured out how to leave the one they’re in.
I do BPO work across east and south King County every day, and the question I hear more than any other from move-up sellers isn’t “what’s my house worth.” It’s “how do I not end up homeless for three weeks between closings.” Fair question. The honest answer is that selling and buying at the same time is one of the most stressful parts of a real estate transaction, and it’s also one of the most manageable, if you pick the right strategy for your situation instead of guessing your way through it.
This post is the hub for that decision. There are really only three ways to structure a double move in King County right now, and which one fits you depends on your equity, your risk tolerance, and how competitive the market is in the city you’re buying into. I’ll walk through all three here, then point you to the deep-dive posts on financing and paperwork so you’re not reading a 4,000-word article when you just need to know which lane to pick.
The Three Ways to Structure a Double Move
Every version of “how do I buy and sell at the same time” comes down to one of three structures. There’s no fourth secret option a lender is hiding from you. It’s sequencing, and each sequence trades speed for cost or cost for risk.
Sell First, Then Buy
You put your current home on the market, get it under contract, and negotiate a rent-back period from your buyer so you can stay in the house while you shop for your next one. This is the most common approach I see in King County right now, and it’s the one I recommend to most sellers unless there’s a specific reason not to.
The math works because King County inventory is still tight enough that sellers have leverage to ask for a rent-back, and buyers are used to granting one. A 30 to 45 day rent-back on a $700,000 to $900,000 South or East King County sale typically runs somewhere in the range of $150 to $200 per day, based on the buyer’s carrying costs. That’s real money, but it’s a fraction of what a bridge loan costs, and you’re not carrying two mortgages while you wait.
The tradeoff: you don’t have a home lined up when you accept an offer on your current one. If the market in your target city is competitive, you’re shopping on a clock, and that pressure can push you toward a house you like instead of the one you actually want.
Buy First With a Bridge Loan or HELOC
You tap your current home’s equity through a bridge loan or a home equity line of credit, use that cash to buy your next home without a sale contingency, then sell your current home once you’ve moved. This is the fastest path and the one that makes your offer strongest in a multiple-offer situation, because a non-contingent offer backed by cash beats a contingent offer every time.
It’s also the most expensive option. Bridge loans in this market run roughly 10 to 13% APR plus 1.5 to 3 points, and you’re paying two mortgage payments during the overlap. On a fully drawn $500,000 bridge loan held for four months at 12%, you’re looking at close to $30,000 in interest and fees before you’ve paid a single closing cost on either house. A HELOC is usually cheaper than a bridge loan if you already have one in place or can get approved quickly, but it still means carrying two housing payments for however long the overlap lasts.
I steer buy-first toward sellers with substantial equity and a low tolerance for losing the house they want. If you’re in Bellevue or Sammamish with 40% or more equity in your current home, this option is worth a serious look. If your equity is tighter, the carrying cost eats into the math fast. For the full head-to-head breakdown of bridge loans versus HELOCs versus cash-out refinancing, including real numbers on cost and timing, read that guide before you commit to either one.
Write a Contingent Offer
You make an offer on your next home that’s contingent on selling your current one, using NWMLS Form 22B. This is the cheapest option on paper because you’re not paying bridge loan interest or a rent-back fee. It’s also the weakest offer you can put in front of a seller, because most sellers will attach a kick-out clause that lets them keep marketing the house and gives you 48 to 72 hours to remove your contingency if a better offer shows up.
Contingent offers do work in King County when the market softens enough that sellers have fewer competing offers to choose from. At around 2.9 months of supply, which is close to where several South King County submarkets have sat this year, a clean contingent offer with a strong sold-comp price and a short kick-out window can get accepted. In Bellevue or Sammamish, where competition stays tighter, a contingent offer is a much harder sell.
The mechanics of writing a contingent offer sellers will actually accept, including how to structure the kick-out timeline and price it competitively, are covered in my contingent offer guide. That one is worth reading closely before you write the offer, because the defaults built into the standard form can work against you if you leave them blank.
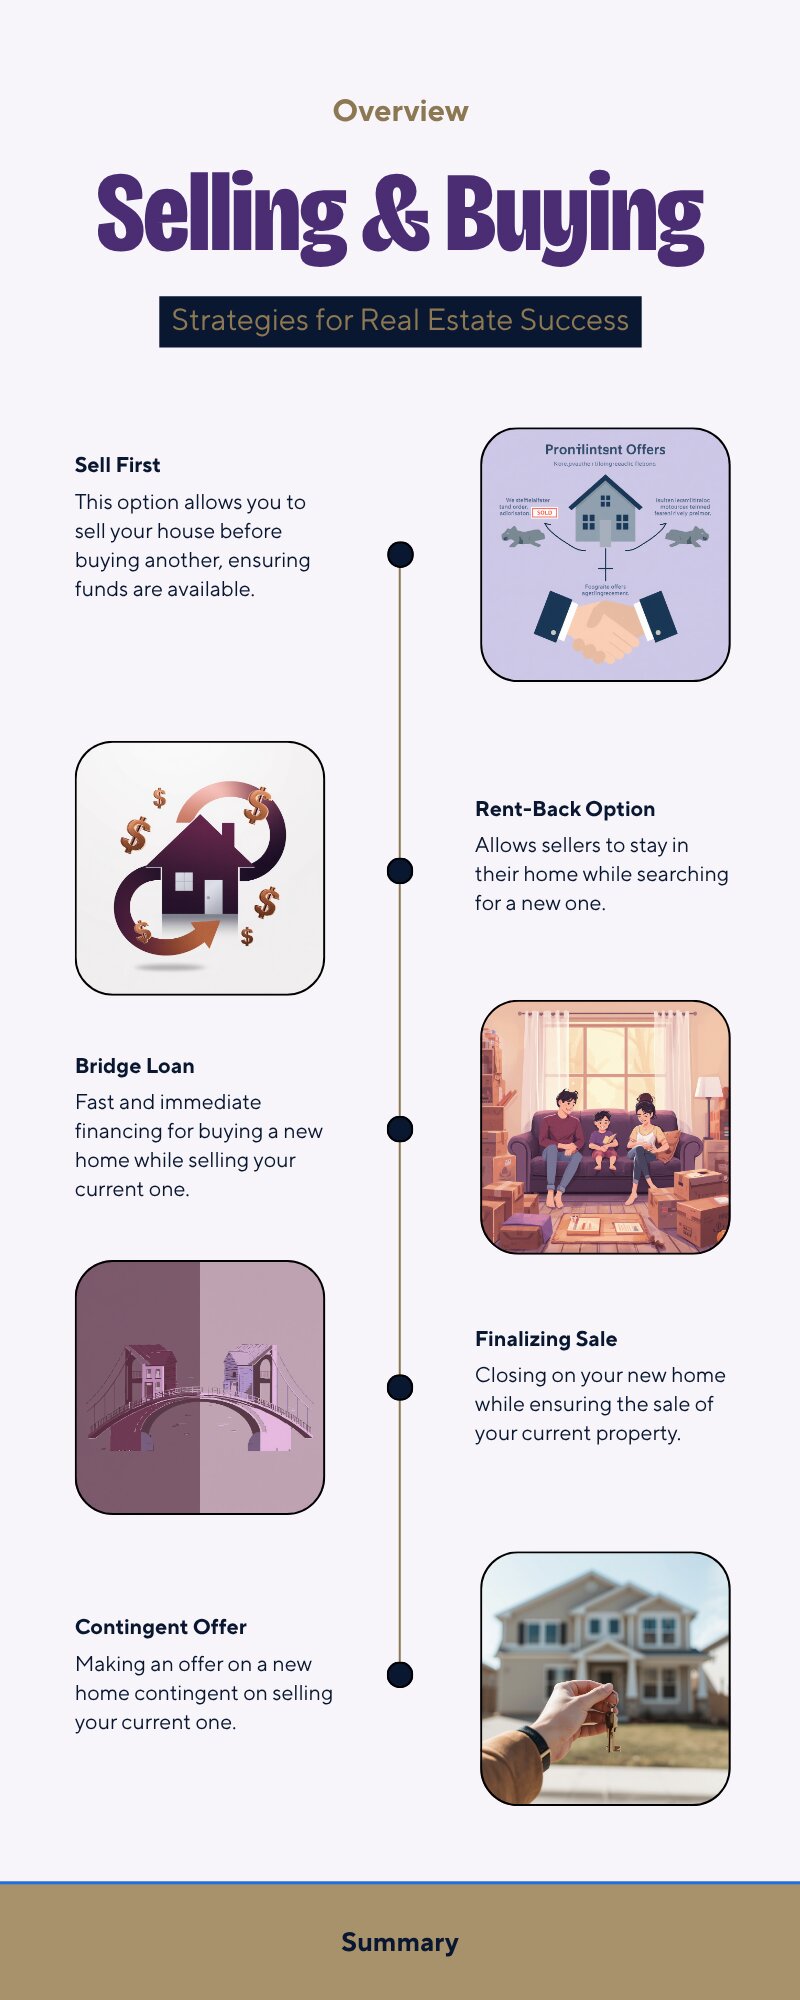
Each double-move strategy trades speed for cost, or cost for risk. Pick based on your equity and timeline.
How to Pick the Right Strategy
Start with your equity. If you’re sitting on 35% or more equity in your current home and you can’t stomach losing the house you want, buy-first is worth pricing out. If your equity is more modest, or you’d rather not carry two payments even for a few months, sell-first with a rent-back is almost always the better move.
Next, look at the market you’re buying into, not the market you’re selling in. A seller in Auburn with a contingent offer looking at a home in Kent has decent odds. That same seller looking at a home in Bellevue is competing against buyers who can close without any contingency at all, and the contingent offer usually loses.
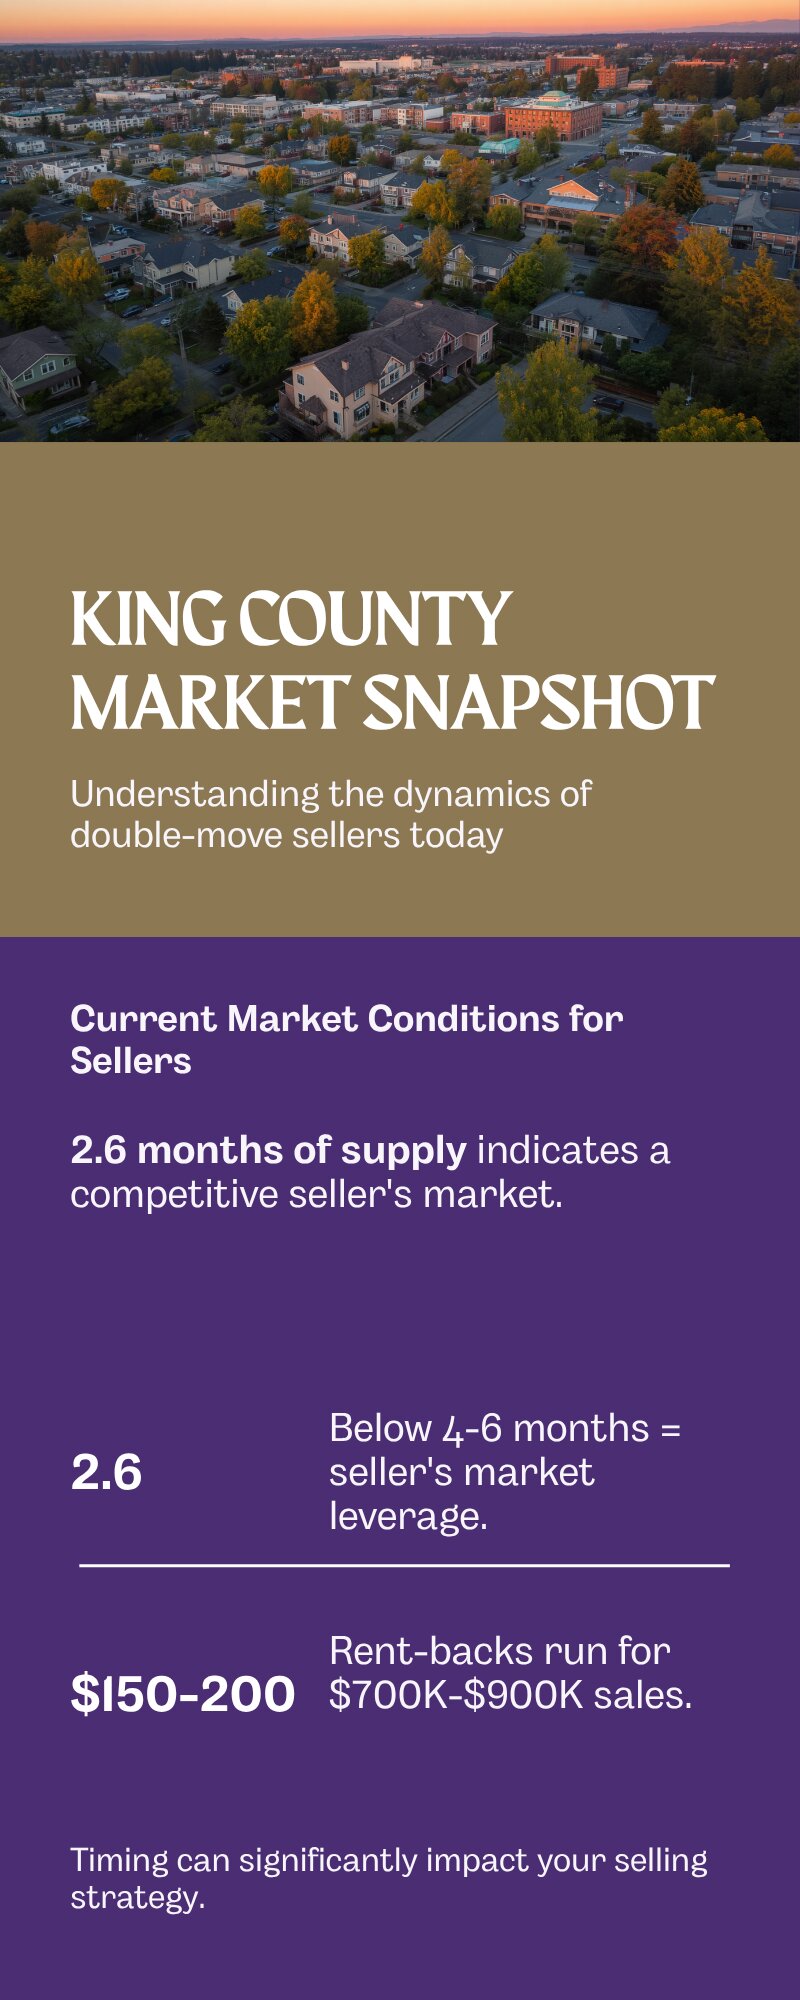
At current King County inventory levels, sell-first with a rent-back is the default play for most sellers.
Finally, be honest about your timeline. If you need certainty about where you’re living on a specific date, whether that’s a school year, a job start date, or a lease ending, sell-first with a rent-back gives you the most control, because you’re not depending on finding the right house in a compressed window.
From the Field
Pricing right the first time matters most when you’re on someone else’s clock.
What This Means for You
If you’re planning a move in King County in the next few months, don’t pick a strategy because it’s what a friend did or because it sounds simpler. Run the actual numbers on your equity, price out what a bridge loan or rent-back would really cost, and look honestly at how competitive your target city is right now. That’s the difference between a double move that goes smoothly and one that costs you money or the house you wanted.
If you’re specifically weighing whether this is even the right time to trade up, my Renton move-up guide and the full cost-to-sell breakdown for Washington sellers are the two best next reads. Between the three, you’ll have the full picture on cost, timing, and whether the move pencils out before you talk to a lender.
FAQ
Can I make a non-contingent offer if my current home hasn’t sold yet?
Yes, if you have another way to fund the purchase, most often a bridge loan, a HELOC, or enough cash reserves to carry both payments. Without one of those, you’ll need a sale contingency, which puts you at a disadvantage against other buyers in a competitive King County market.
How long does a rent-back typically last after I sell my King County home?
Most rent-backs I negotiate run 30 to 45 days, though some buyers will agree to 60 days depending on their own timeline and financing. The daily rate is tied to the buyer’s carrying cost on the home, not a fixed number, so it varies by sale price and city.
Is a HELOC or a bridge loan cheaper for buying before I sell?
A HELOC is usually cheaper if you already qualify and have one set up, since it avoids some of the fees baked into a dedicated bridge loan product. A bridge loan can move faster if you need funds quickly and don’t already have a HELOC in place. Both carry real cost, so run the numbers on your specific situation before committing to either.
What happens if my current home doesn’t sell during a contingent offer’s window?
Under NWMLS Form 22B, if you don’t get your home under a valid purchase and sale agreement within the negotiated window, and the seller invokes a kick-out clause after receiving a competing offer, you typically have 48 to 72 hours to remove your contingency or the seller can move forward with the other buyer. You’d get your earnest money back, but you’d lose the house.
Do I need to use the same agent for both my sale and my purchase?
You don’t have to, but it usually helps. Coordinating two closings means your listing agent and your buyer’s agent, plus both title companies and both lenders, all need to stay in sync on dates. One agent managing both sides of your transaction can tighten that coordination significantly.
Your guide to life outside Seattle.
253-350-0045 ·
greg@livingoutsideseattle.com ·
www.livingoutsideseattle.com
