

 Facebook
 X
 Pinterest
 Copy Link
Knock vs. Orchard vs. HomeLight: Who Lets You Keep Your Agent in King County
I get asked about these programs constantly by King County sellers who found them through a Google search or a Facebook ad. Knock. Orchard. HomeLight’s Buy Before You Sell. They all promise the same thing: buy your next house before you sell your current one, skip the contingent offer, move once instead of twice.
All three actually operate here, which surprises some sellers who’ve read older posts claiming otherwise. What most comparisons miss is a fairer question than “which is cheapest”: every one of these transactions still involves a real estate agent and a commission. The programs just handle that piece differently, and that difference matters more than the headline fee percentage.
What These Programs Actually Solve
Every one of these programs exists to fix the same problem: you found the house you want, but your equity is still locked inside the house you’re living in. In King County right now, that problem is real. The county’s median sold price sits around $845,000, months of supply is running about 3.9, and the median days on market is 21. That’s still a market where a clean, non-contingent offer beats a contingent one most of the time, especially in tighter Eastside segments like Bellevue and Sammamish.
These three programs are one path through a bigger decision. If you’re weighing whether to sell and buy at the same time at all, or how buy-first programs stack up against a straightforward bridge loan or HELOC, those posts cover the broader framework. This one stays focused on the three named programs themselves.
So the appeal makes sense. You get access to your equity before your old house sells, you make a stronger offer on the new one, and you avoid living through two moves in three months. The part that gets skipped over is that “buy before you sell” isn’t one product. It’s three different structures, and they handle your real estate agent relationship in three different ways.
The Real Difference: Who You’re Required to Work With
Here’s what most comparisons of these three programs get wrong. They quote each program’s fee side by side as if that fee is the total cost, when in every case you’re also paying a real estate agent to actually list and sell your home. The programs just differ in whether you get to choose that agent.
Knock is the most flexible: Knock’s own FAQ confirms “you can work with any agent for listing your current home and the purchase of your new home.” Their roughly 2.25% fee is a separate charge on top of whatever commission you negotiate with your own agent.
HomeLight works through a network of local agents. You’re not required to use your existing agent, and you’re typically matched with a “certified HomeLight Buy Before You Sell agent” from their network. That agent still earns a standard commission, separate from HomeLight’s flat 2.4% fee.
Orchard is the one true exception: their own FAQ states plainly that “you will need to use an Orchard agent to help you sell your current home” (you can use an outside agent to buy, but not to sell). Because Orchard is acting as your listing brokerage, their quoted fee bundles a full 3-6% commission together with a separate 1.9-2.4% program fee. It looks like one number, but it’s doing the job of two separate charges the other programs keep apart.
Once you line these up honestly, the total cost gap between the three narrows considerably. Orchard isn’t necessarily the most expensive option, it’s the one where the agent commission is baked into the number you see instead of being a separate line item you’d pay Knock’s or HomeLight’s agent anyway.
Knock: Bring Your Own Agent
Knock’s Home Swap program is, at its core, a bridge loan. You get funds to cover your down payment and carrying costs on the new home while your old one sits on the market, and in some structures you can rent back your new home briefly during the transition.
The program fee: a fixed fee of about 2.25% of your new home’s purchase price, plus roughly $1,850 in estimated closing costs that vary by loan amount and state requirements. On a $700,000 replacement home, that fee alone runs close to $15,750, before closing costs. Your listing agent’s commission is separate and negotiable, since you’re free to use whichever agent you already trust.
The safety net: if your old home hasn’t sold within six months, Knock will make a non-contingent backup offer to buy it from you directly.
So what does this mean for you? Knock is available for sellers listing in Washington state, including King County. Because you keep your own agent, this is a good fit if you already have a relationship you don’t want to give up. If your home is priced right and likely to move inside that six-month window, the backup offer is more of an insurance policy than something you expect to use.
Orchard: Their Agent, Bundled Pricing
Orchard’s Move First program does operate in the Seattle metro area, including King County. Orchard expanded into Washington in 2022 as part of its push into the Western U.S., and its own site currently lists Seattle among its active selling markets. If you’ve read that Orchard skips this market entirely, that’s out of date.
What’s different about Orchard is that you’re required to list with Orchard’s own agents. That’s why their pricing looks higher at first glance: a 3-6% brokerage commission plus a separate 1.9-2.4% program fee (minimum $9,000). On a $700,000 sale, that’s roughly $21,000 to $42,000 in commission plus $13,300 to $16,800 in program fee, for a combined total in the $34,000 to $59,000 range. But that commission is money you’d be paying an agent under any of these three programs anyway, it’s just visible here instead of being a separate line item.
The safety net: if your home hasn’t sold within 120 days, Orchard extends a guaranteed backup offer, with the option to extend the listing period further on some plans.
So what does this mean for you? Orchard is a legitimate option in King County, not a wasted application. The real trade-off isn’t price, it’s that you give up your choice of listing agent to get it. If you already have an agent relationship you value, that’s the real cost of Orchard, more than the dollar figure on the quote.
HomeLight: A Network Agent, Not Necessarily Your Own
HomeLight’s Buy Before You Sell program works through a network of local agents and lenders rather than an in-house brokerage model. You get an equity unlock to use toward your new down payment, you buy first, then an agent lists and sells the old home on the open market.
The program fee: a flat fee of 2.4% of your departing home’s sale price in most markets, with regional variations (Florida runs 2.9%, parts of the Chicago area charge a flat $1,500 instead). On an $845,000 King County median-priced home, that 2.4% fee comes out to roughly $20,280, separate from your agent’s commission.
The safety net: if your home hasn’t sold within 90 to 120 days depending on the source you check, HomeLight extends a backup purchase offer. Under their “Upside Protection” structure, if the home eventually sells for more than that backup offer, you get the difference back, minus HomeLight’s costs and the agent’s commission.
So what does this mean for you? HomeLight is available in Washington state, and the flat 2.4% program fee is simple to run the math on. But confirm up front whether you’ll be matched with a HomeLight network agent or whether your own agent can participate, since that varies and directly affects whether you keep the representation and local market knowledge you already have in King County’s submarket-by-submarket pricing.
The Local Angle: What This Costs a King County Seller Specifically
Run the real numbers on a $700,000 King County departing home and a $700,000 replacement home, and here’s how it breaks down once agent commission is accounted for on all three.
Knock Home Swap
Program fee: about 2.25% of the new home’s price (~$15,750 on a $700K purchase) plus roughly $1,850 in closing costs, plus your own agent’s commission (typically 2.5-3% listing side, negotiated separately).
Agent choice: any agent you want. Backup offer window: 6 months.
HomeLight Buy Before You Sell
Program fee: flat 2.4% of the departing home’s sale price (~$16,800 on a $700K sale), plus your agent’s commission (network-matched in most cases, confirm up front).
Agent choice: typically a network agent. Backup offer window: 90 to 120 days.
Orchard Move First
All-in fee: 3-6% brokerage commission (~$21,000 to $42,000 on a $700K sale) plus a 1.9-2.4% program fee, $9,000 minimum (~$13,300 to $16,800). Combined total: roughly $34,300 to $58,800, but this figure already includes the agent commission the other two programs charge separately.
Agent choice: must use Orchard’s in-house agent to sell. Backup offer window: 120 days.
Add a comparable commission to the Knock and HomeLight numbers and the three programs land closer together than the headline fees suggest. The number that should drive your decision isn’t which fee percentage is smallest, it’s whether keeping your own agent (Knock), accepting a network match (HomeLight), or trading agent choice for a single bundled number (Orchard) fits how you want to sell.
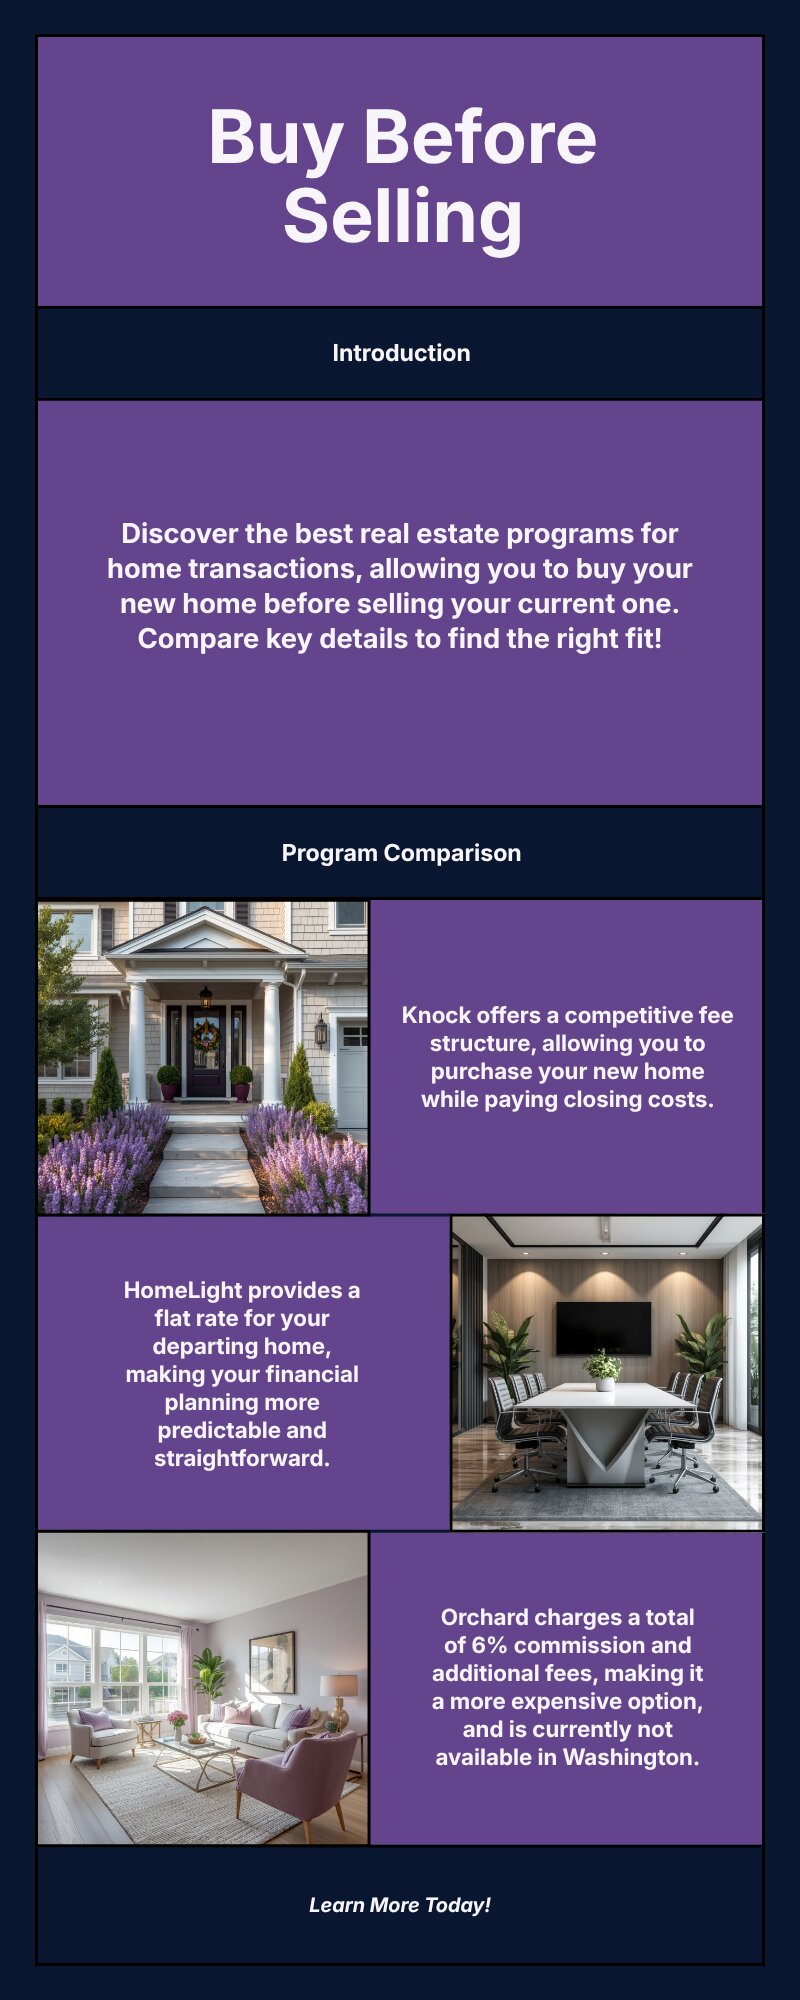
All three programs operate in King County, and once agent commission is counted consistently, their total costs are closer than a fee-only comparison suggests.
Compare any of those numbers to a bridge loan or HELOC, and the math often tilts further in your favor if you have the equity and timeline flexibility for a more traditional structure. I’ve written about how bridge loans, HELOCs, and buy-first programs stack up against each other in more detail. It’s also worth asking your lender about lesser-known regional buy-first and bridge programs beyond these three national brands. Several exist, availability and terms vary a lot, and your own agent or lender will know what’s currently on offer for King County.
What This Means for You
If you’re a King County seller with solid equity in your current home and a property that will sell inside 60 to 90 days at a fair price, look hard at a HELOC or bridge loan before any of these three programs. You’ll typically pay less in total cost, and you keep full control of your sale timeline instead of a program’s backup-offer clock.
If your equity is thinner, your timeline is tight, or you need the certainty of a guaranteed backup offer to make a competitive, non-contingent offer on your next home, all three programs are real options here. Start with the agent-choice question, not the fee percentage: do you want to keep your current agent (Knock), are you open to a matched agent (HomeLight), or is a single bundled number worth giving up that choice (Orchard)? Then run the actual numbers, including commission, on your specific purchase and sale prices.
Either way, don’t sign up for a program based on a “top 3 options” article that compares program fees without accounting for who’s earning the commission. That’s the mistake I see most often, and it’s an easy one to avoid once you’ve seen how the fees actually break down.
FAQ
Is Orchard’s Move First program available in King County, Washington?
Yes. Orchard expanded into the Seattle metro area in 2022 and currently lists Seattle, WA among its active Move First markets, along with Washington state more broadly for its buying services. It’s a real option for King County sellers, though it requires listing with Orchard’s own in-house agent.
Can I use my own real estate agent with Knock, HomeLight, or Orchard?
With Knock, yes, their own FAQ confirms you can work with any agent for both the sale and purchase. With HomeLight, you’re typically matched with an agent from their network; confirm up front whether your existing agent can participate. With Orchard, no: you must use an Orchard agent to sell your current home, though you can use an outside agent to buy your next one.
Is Orchard actually more expensive than Knock or HomeLight?
Not necessarily. Orchard’s quoted fee looks higher because it bundles a full 3-6% agent commission together with its 1.9-2.4% program fee. Knock and HomeLight quote a smaller program fee, but you still pay a separate agent commission on top of it under those programs too. Once commission is counted consistently across all three, the total costs land in a similar range.
How much does Knock’s Home Swap program cost in King County?
Knock charges a fixed program fee of about 2.25% of your new home’s purchase price, plus an estimated $1,850 in closing costs. On a $700,000 replacement home, that’s roughly $17,600 in program fees, plus your own agent’s commission negotiated separately.
What happens if my home doesn’t sell in time with these programs?
Knock provides a non-contingent backup offer if your home hasn’t sold within six months. HomeLight’s window runs 90 to 120 days, and Orchard’s runs 120 days with a possible extension. All three backup offers typically come in below what a well-priced, patiently marketed open-market sale would fetch.
Is a bridge loan or HELOC cheaper than these buy-first programs?
Often, yes, if you have enough equity and a realistic sale timeline. Bridge loans and HELOCs don’t carry a program fee tied to a percentage of your home’s value, and you still choose your own agent. Costs run more toward loan origination and interest. I break down the full comparison in my guide to buy-first financing options in King County.
Are Knock, Orchard, and HomeLight the only buy-first programs available in King County?
No. These three are the best-known brands, but several lesser-known mortgage lenders offer similar bridge-style programs with their own fee structures and availability. Ask your agent or preferred lender what’s currently offered in King County before assuming these three are your only options.
Your guide to life outside Seattle.
253-350-0045 ·
greg@livingoutsideseattle.com ·
www.livingoutsideseattle.com
Sell and Buy a House at the Same Time in King County
Most people find their next house before they’ve figured out how to leave the one they’re in.
I do BPO work across east and south King County every day, and the question I hear more than any other from move-up sellers isn’t “what’s my house worth.” It’s “how do I not end up homeless for three weeks between closings.” Fair question. The honest answer is that selling and buying at the same time is one of the most stressful parts of a real estate transaction, and it’s also one of the most manageable, if you pick the right strategy for your situation instead of guessing your way through it.
This post is the hub for that decision. There are really only three ways to structure a double move in King County right now, and which one fits you depends on your equity, your risk tolerance, and how competitive the market is in the city you’re buying into. I’ll walk through all three here, then point you to the deep-dive posts on financing and paperwork so you’re not reading a 4,000-word article when you just need to know which lane to pick.
The Three Ways to Structure a Double Move
Every version of “how do I buy and sell at the same time” comes down to one of three structures. There’s no fourth secret option a lender is hiding from you. It’s sequencing, and each sequence trades speed for cost or cost for risk.
Sell First, Then Buy
You put your current home on the market, get it under contract, and negotiate a rent-back period from your buyer so you can stay in the house while you shop for your next one. This is the most common approach I see in King County right now, and it’s the one I recommend to most sellers unless there’s a specific reason not to.
The math works because King County inventory is still tight enough that sellers have leverage to ask for a rent-back, and buyers are used to granting one. A 30 to 45 day rent-back on a $700,000 to $900,000 South or East King County sale typically runs somewhere in the range of $150 to $200 per day, based on the buyer’s carrying costs. That’s real money, but it’s a fraction of what a bridge loan costs, and you’re not carrying two mortgages while you wait.
The tradeoff: you don’t have a home lined up when you accept an offer on your current one. If the market in your target city is competitive, you’re shopping on a clock, and that pressure can push you toward a house you like instead of the one you actually want.
Buy First With a Bridge Loan or HELOC
You tap your current home’s equity through a bridge loan or a home equity line of credit, use that cash to buy your next home without a sale contingency, then sell your current home once you’ve moved. This is the fastest path and the one that makes your offer strongest in a multiple-offer situation, because a non-contingent offer backed by cash beats a contingent offer every time.
It’s also the most expensive option. Bridge loans in this market run roughly 10 to 13% APR plus 1.5 to 3 points, and you’re paying two mortgage payments during the overlap. On a fully drawn $500,000 bridge loan held for four months at 12%, you’re looking at close to $30,000 in interest and fees before you’ve paid a single closing cost on either house. A HELOC is usually cheaper than a bridge loan if you already have one in place or can get approved quickly, but it still means carrying two housing payments for however long the overlap lasts.
I steer buy-first toward sellers with substantial equity and a low tolerance for losing the house they want. If you’re in Bellevue or Sammamish with 40% or more equity in your current home, this option is worth a serious look. If your equity is tighter, the carrying cost eats into the math fast. For the full head-to-head breakdown of bridge loans versus HELOCs versus cash-out refinancing, including real numbers on cost and timing, read that guide before you commit to either one.
Write a Contingent Offer
You make an offer on your next home that’s contingent on selling your current one, using NWMLS Form 22B. This is the cheapest option on paper because you’re not paying bridge loan interest or a rent-back fee. It’s also the weakest offer you can put in front of a seller, because most sellers will attach a kick-out clause that lets them keep marketing the house and gives you 48 to 72 hours to remove your contingency if a better offer shows up.
Contingent offers do work in King County when the market softens enough that sellers have fewer competing offers to choose from. At around 2.9 months of supply, which is close to where several South King County submarkets have sat this year, a clean contingent offer with a strong sold-comp price and a short kick-out window can get accepted. In Bellevue or Sammamish, where competition stays tighter, a contingent offer is a much harder sell.
The mechanics of writing a contingent offer sellers will actually accept, including how to structure the kick-out timeline and price it competitively, are covered in my contingent offer guide. That one is worth reading closely before you write the offer, because the defaults built into the standard form can work against you if you leave them blank.
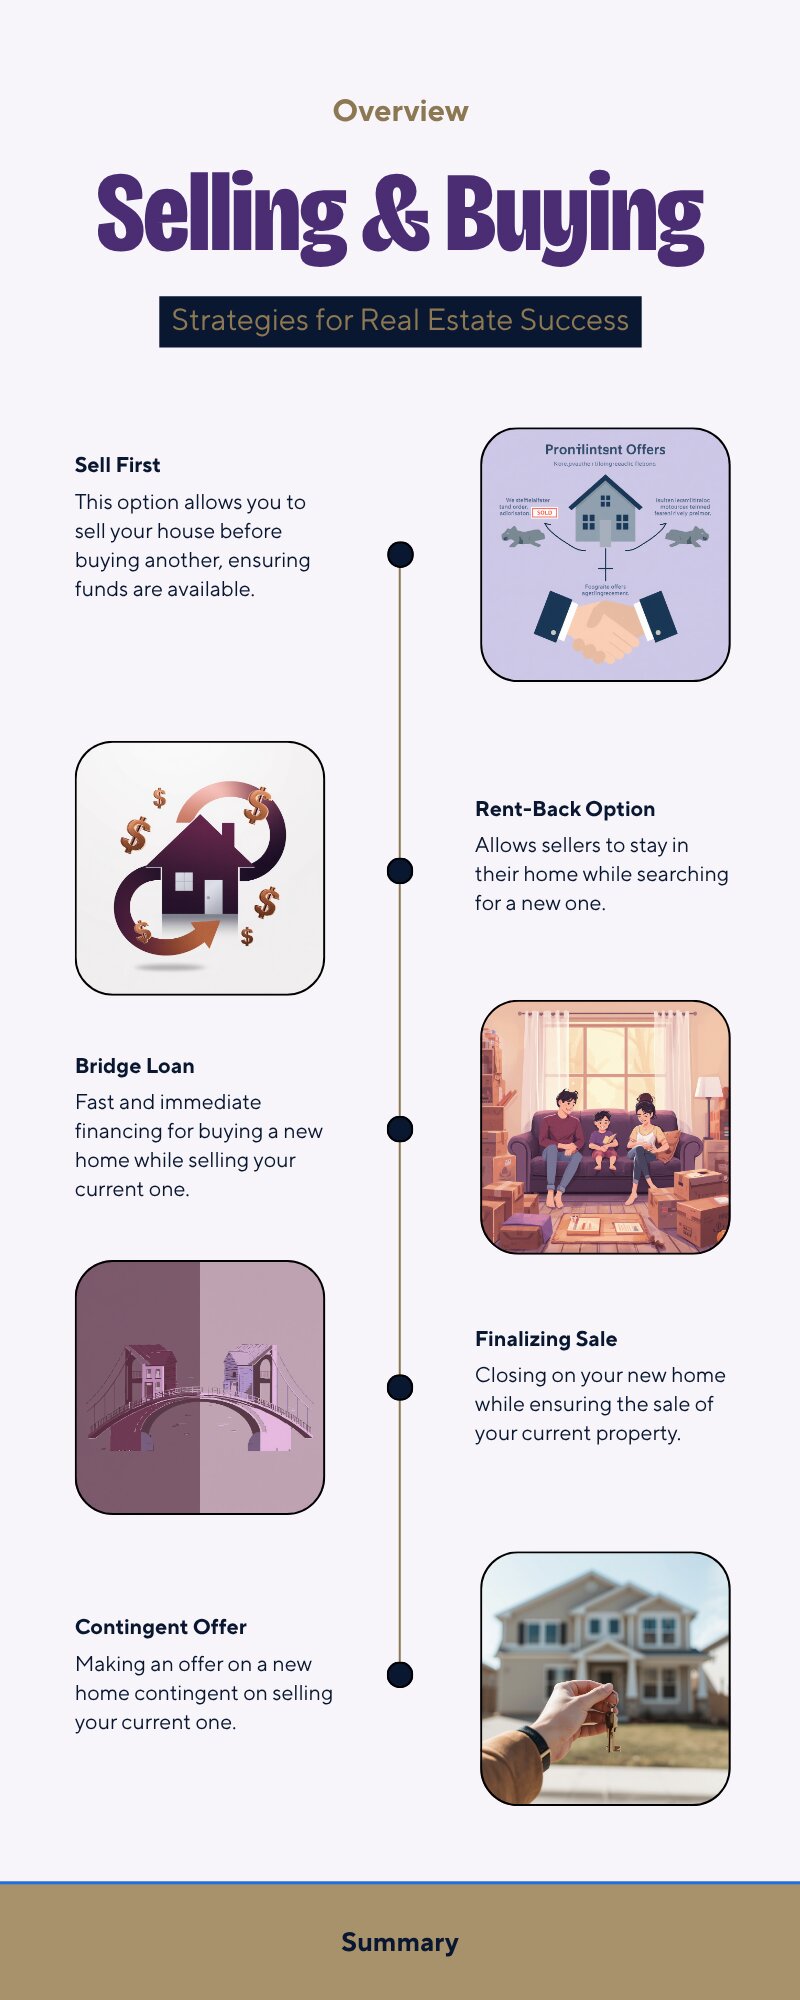
Each double-move strategy trades speed for cost, or cost for risk. Pick based on your equity and timeline.
How to Pick the Right Strategy
Start with your equity. If you’re sitting on 35% or more equity in your current home and you can’t stomach losing the house you want, buy-first is worth pricing out. If your equity is more modest, or you’d rather not carry two payments even for a few months, sell-first with a rent-back is almost always the better move.
Next, look at the market you’re buying into, not the market you’re selling in. A seller in Auburn with a contingent offer looking at a home in Kent has decent odds. That same seller looking at a home in Bellevue is competing against buyers who can close without any contingency at all, and the contingent offer usually loses.
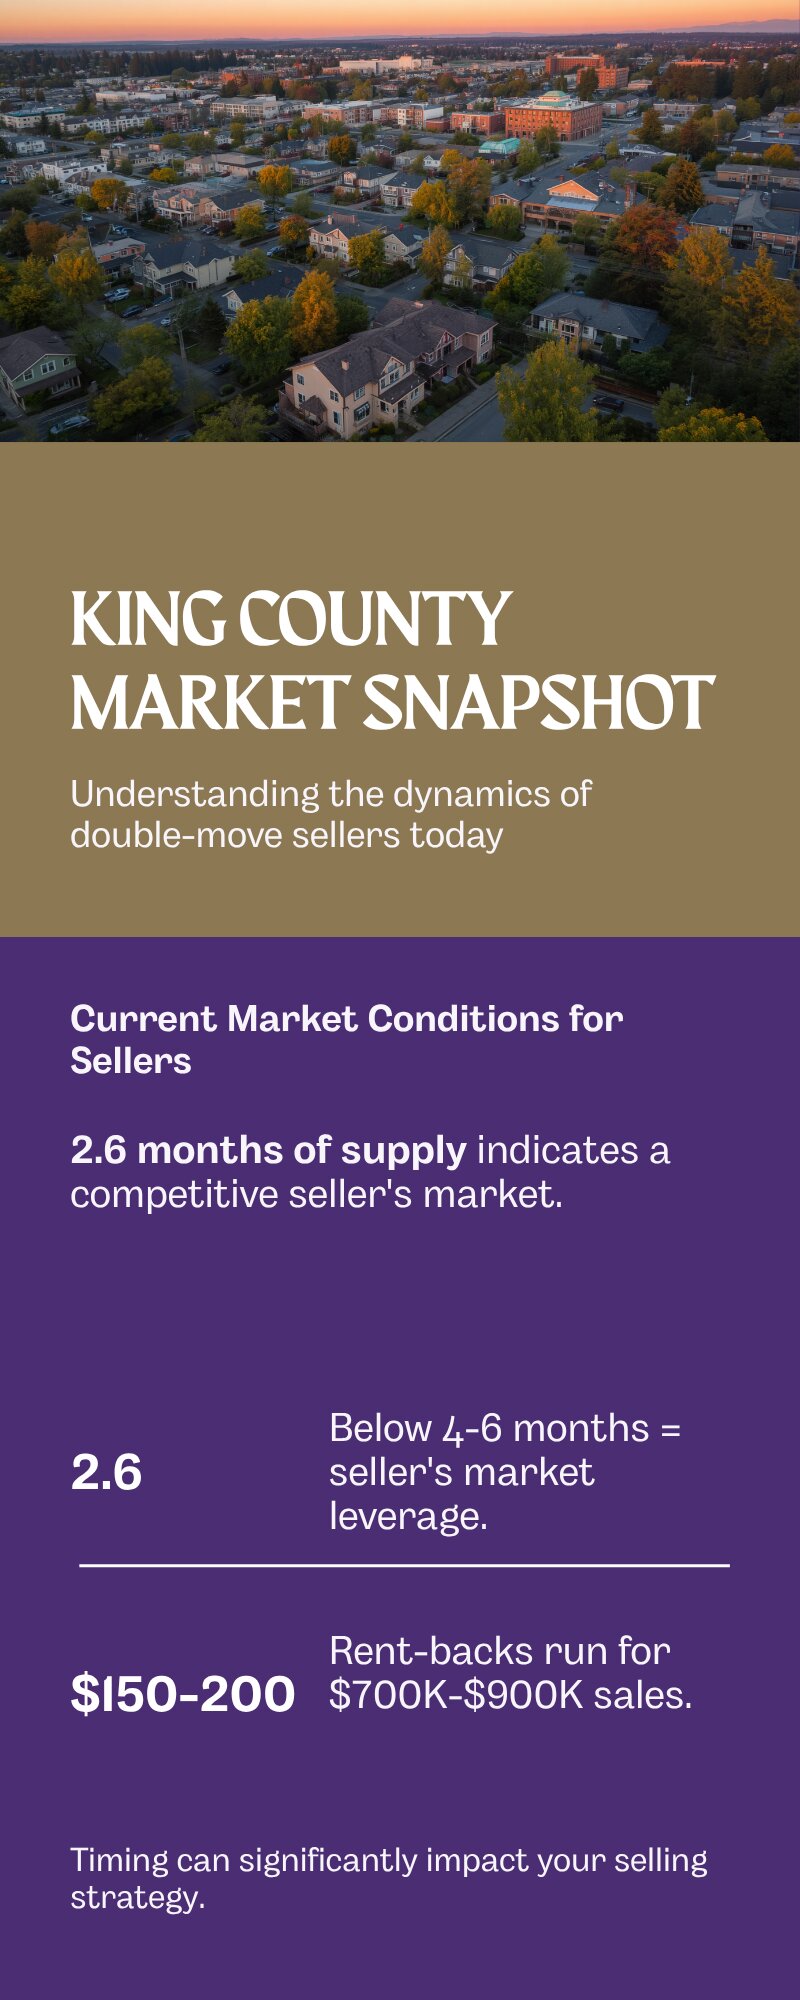
At current King County inventory levels, sell-first with a rent-back is the default play for most sellers.
Finally, be honest about your timeline. If you need certainty about where you’re living on a specific date, whether that’s a school year, a job start date, or a lease ending, sell-first with a rent-back gives you the most control, because you’re not depending on finding the right house in a compressed window.
From the Field
Pricing right the first time matters most when you’re on someone else’s clock.
What This Means for You
If you’re planning a move in King County in the next few months, don’t pick a strategy because it’s what a friend did or because it sounds simpler. Run the actual numbers on your equity, price out what a bridge loan or rent-back would really cost, and look honestly at how competitive your target city is right now. That’s the difference between a double move that goes smoothly and one that costs you money or the house you wanted.
If you’re specifically weighing whether this is even the right time to trade up, my Renton move-up guide and the full cost-to-sell breakdown for Washington sellers are the two best next reads. Between the three, you’ll have the full picture on cost, timing, and whether the move pencils out before you talk to a lender.
FAQ
Can I make a non-contingent offer if my current home hasn’t sold yet?
Yes, if you have another way to fund the purchase, most often a bridge loan, a HELOC, or enough cash reserves to carry both payments. Without one of those, you’ll need a sale contingency, which puts you at a disadvantage against other buyers in a competitive King County market.
How long does a rent-back typically last after I sell my King County home?
Most rent-backs I negotiate run 30 to 45 days, though some buyers will agree to 60 days depending on their own timeline and financing. The daily rate is tied to the buyer’s carrying cost on the home, not a fixed number, so it varies by sale price and city.
Is a HELOC or a bridge loan cheaper for buying before I sell?
A HELOC is usually cheaper if you already qualify and have one set up, since it avoids some of the fees baked into a dedicated bridge loan product. A bridge loan can move faster if you need funds quickly and don’t already have a HELOC in place. Both carry real cost, so run the numbers on your specific situation before committing to either.
What happens if my current home doesn’t sell during a contingent offer’s window?
Under NWMLS Form 22B, if you don’t get your home under a valid purchase and sale agreement within the negotiated window, and the seller invokes a kick-out clause after receiving a competing offer, you typically have 48 to 72 hours to remove your contingency or the seller can move forward with the other buyer. You’d get your earnest money back, but you’d lose the house.
Do I need to use the same agent for both my sale and my purchase?
You don’t have to, but it usually helps. Coordinating two closings means your listing agent and your buyer’s agent, plus both title companies and both lenders, all need to stay in sync on dates. One agent managing both sides of your transaction can tighten that coordination significantly.
Your guide to life outside Seattle.
253-350-0045 ·
greg@livingoutsideseattle.com ·
www.livingoutsideseattle.com
