AuburnProbate ResourcesSeller Resources August 24, 2026

Probate Sale vs. Rental: An Auburn Example (2026)

I’ve walked several probate clients through this exact decision, often multiple heirs with different opinions about what to do with a family home. The emotional pull toward keeping it is real. The financial case usually points the other way, but not always, and it depends on your specific situation.

The Case for Selling

Selling through probate is the cleaner path in almost every practical sense. You get one transaction, one closing, and a defined end point. If there are multiple heirs, this also avoids the ongoing complexity of shared ownership and shared decision-making on a rental property, which is where family disagreements often surface years down the road, not at the time of inheritance.

Financially, stepped-up basis usually means minimal capital gains tax if you sell reasonably soon after inheriting. I cover exactly how that works in my inherited home tax math guide, though that piece focuses on higher-value Eastside homes specifically. The same stepped-up basis principle applies at Auburn’s price point too; the dollar amounts are just smaller.

The Case for Renting

Renting makes sense when you want ongoing income, when the local rental market strongly favors landlords, or when one or more heirs specifically want to hold real estate as a long-term investment rather than cash out. Auburn’s rental market is generally healthy given the city’s affordability and proximity to employment centers, so this isn’t a bad rental market by any means.

But renting means ongoing responsibility. Tenant management, maintenance, vacancy risk, and the accounting complexity of shared ownership among multiple heirs all continue indefinitely. If even one heir wants to sell and the others want to hold, you’re now negotiating a buyout or dealing with a forced sale down the road, a more complicated version of the decision you’re facing right now.
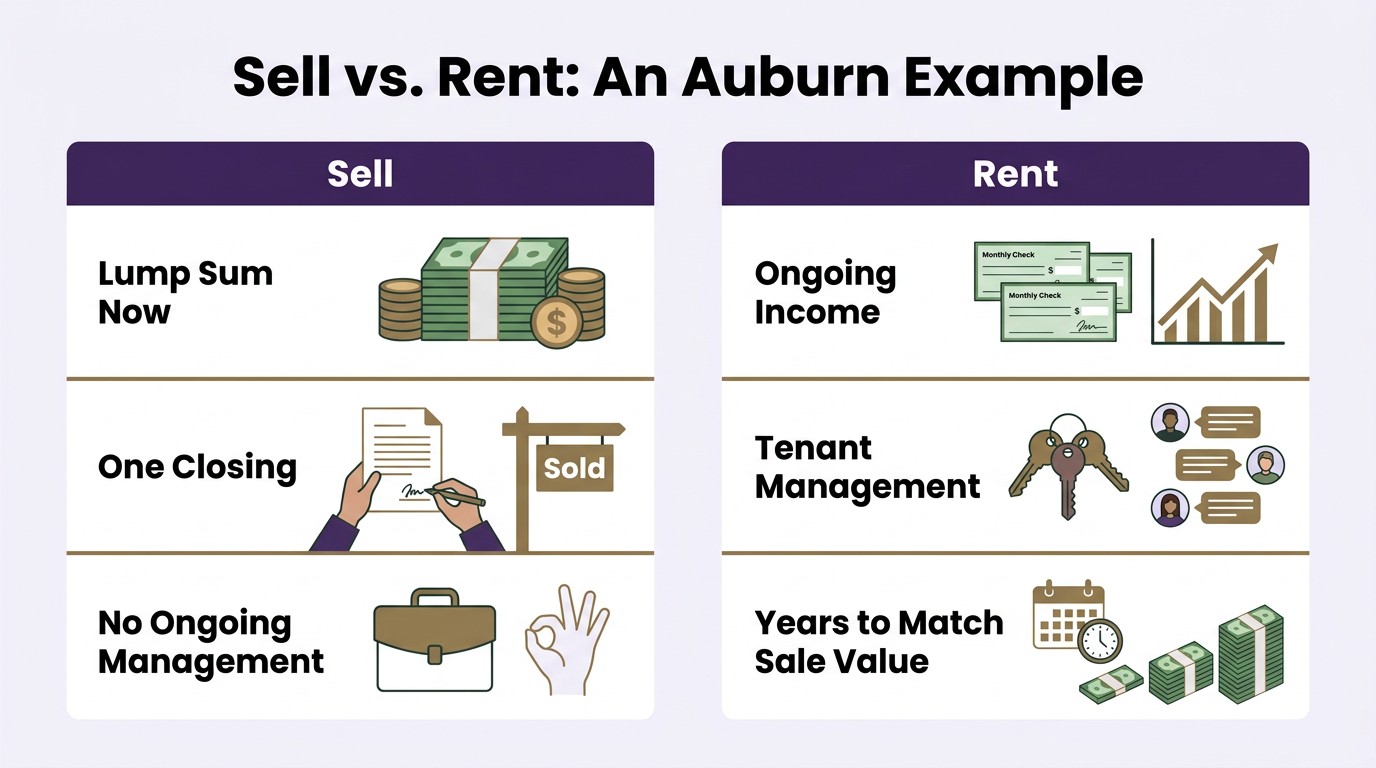
Probate sell vs rent comparison chart Auburn WA 2026

Selling delivers a lump sum fast; renting ties you to ongoing management and a longer path to the same value.

Running the Actual Numbers

At Auburn’s median sale price around $592,500, selling nets you that amount minus commission, REET, and closing costs, typically landing in the 90 to 92 percent range of sale price after standard costs. That’s a defined number you can act on immediately.

Renting requires estimating monthly rental income against mortgage payoff status (many inherited homes are owned free and clear, which changes this math significantly), property taxes, insurance, maintenance reserves, and property management if you’re not doing it yourself. If the home is free and clear, rental income minus expenses can generate a reasonable annual return, but it takes years to approach what an immediate sale delivers in a lump sum, and that’s before accounting for the time value of money and the risk of unexpected repairs or vacancy.

Questions to Ask Before Deciding

How many heirs are involved, and do they agree on the decision? Is the home free and clear or still carrying a mortgage? Do any heirs want to occupy the home themselves rather than sell or rent it out? What’s the home’s actual condition, and what would it need before it’s rent-ready or sale-ready? I walk through the repair-versus-sell-as-is decision specifically in my Federal Way sell-as-is guide, which applies to any inherited home regardless of city.

Frequently Asked Questions

Should I sell or rent an inherited home in Auburn?

It depends on your goals and whether all heirs agree. Selling delivers a defined lump sum faster and avoids ongoing management responsibilities. Renting can work well if the home is free and clear, the local rental market is healthy, and heirs specifically want long-term real estate exposure rather than cash.

What happens if heirs disagree about selling versus renting an inherited home?

This is one of the most common probate complications. Some heirs may want to sell for cash now, while others want to hold for rental income. Resolving this usually requires either a buyout of one party’s interest or a broader family agreement, ideally with guidance from an estate attorney rather than an informal understanding.

Is renting out an inherited home in King County a good investment?

It depends heavily on whether the home carries a mortgage, the local rental market, and your tolerance for ongoing management. A mortgage-free inherited home in a healthy rental market can generate reasonable returns, but it takes years to match what an immediate sale delivers as a lump sum.

Your guide to life outside Seattle.

Gregory Dorrell | Coldwell Banker Danforth | WA License #111862
253-350-0045  ·  greg@livingoutsideseattle.com  ·  www.livingoutsideseattle.com

Gregory Dorrell is a licensed real estate broker (WA License #111862) with Coldwell Banker Danforth. Market data from NWMLS, week of August 2, 2026. This post is provided for informational purposes and does not constitute legal or financial advice. Consult an estate attorney and CPA for your specific situation.
Buyer Resources May 18, 2026

Should I Wait to Buy a Home in Auburn WA? The Real Math.

  body { font-family: -apple-system, BlinkMacSystemFont, ‘Segoe UI’, sans-serif; margin: 0; padding: 20px; background: #f0f0f0; }
.preview-wrap { max-width: 860px; margin: 0 auto; background: #fff; border-radius: 8px; overflow: hidden; box-shadow: 0 2px 12px rgba(0,0,0,0.12); }
 

If you’re asking whether you should wait to buy a home in Auburn, WA, you’re not alone. My inbox right now is full of some version of this question: “If rates drop six months from now, won’t I be better off waiting?” It’s a fair question, and it deserves a real answer, not just reassurance. Auburn, Washington is where I want to focus this, because at a $668,000 median price for single-family homes, Auburn is the most affordable entry point across the seven major cities I track in King County. For first-time buyers, that matters. And the math here is closer than most people expect.

What Waiting Six Months Really Costs Auburn Home Buyers

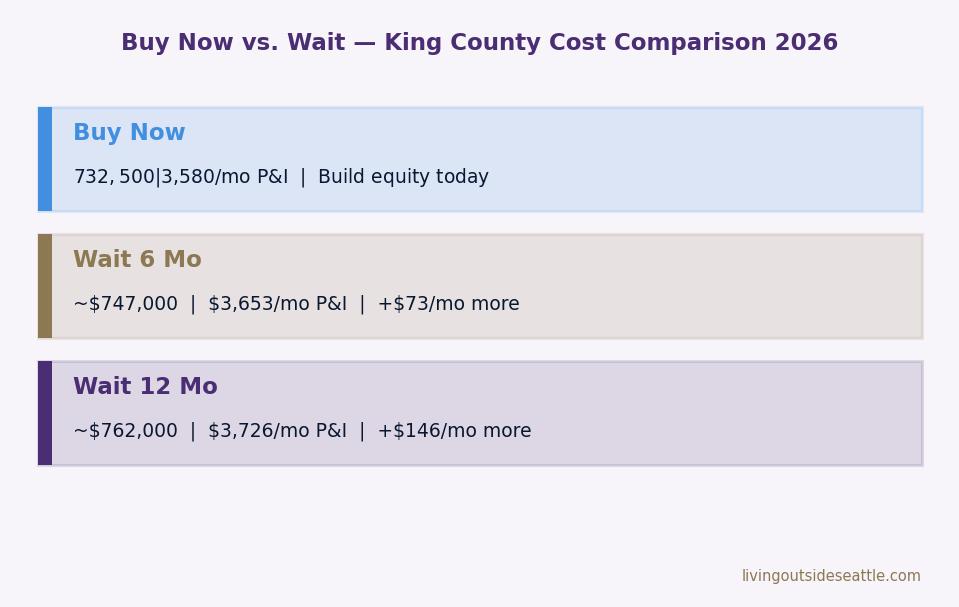
Buy now vs wait 6 months vs wait 12 months ‚Äî King County home buyer cost comparison 2026 Let me walk you through three scenarios. Check my numbers, because this is too important to just take my word for. Scenario 1: Buy now in Auburn at $668,000 with 6.38% rate and 10% down. Loan amount: $601,200. Monthly payment (principal and interest): about $3,840. Down payment: $66,800. Scenario 2: Wait six months, rates drop to 5.38%, but prices rise 3%. New price: $688,240. New loan at 10% down: $619,416. Monthly payment at 5.38%: about $3,710. Down payment: $68,824. You save $130 per month on the payment. But you put $2,024 more upfront and spent six months paying rent or staying in a situation you wanted to leave. Plus you’re six months further from building equity. Scenario 3: Wait six months, rates drop to 5.38%, but prices rise 5% instead. New price: $702,400. New loan: $632,160. Monthly payment at 5.38%: about $3,795. Down payment: $70,240. Now you’re paying $45 more per month than if you’d bought today, even with rates 1% lower. You also put down $3,440 more. You waited six months for that result. Auburn’s current median days on market is 14 days, softer than the King County average of 7 days. That gives you more breathing room than in faster markets like Sammamish (4 days). You have time to make a thoughtful decision. You just don’t have unlimited time.

Why Lower Rates Don’t Mean Lower Home Prices in Auburn

Here’s what most buyers get wrong about the wait-for-rates strategy. They picture a world where rates fall and nobody buys anything in the meantime, so sellers get desperate and cut prices. That’s not what happens. When rates drop, demand increases. More buyers qualify. More buyers have monthly payment headroom. That demand pushes prices up. The two forces move in opposite directions, and prices almost always outpace the benefit of the rate drop. Look at what happened through 2024 and into 2025. Rates eased incrementally, and prices rose. There was no crash followed by a recovery. Steady appreciation as affordability improved. That’s the pattern. King County’s March 2026 median for single-family homes is $995,000. Auburn’s is $668,000. Both have held steady or moved up despite rate pressure. A significant rate drop would likely push both numbers higher, not lower.

When Waiting to Buy a Home Actually Makes Sense

There are real scenarios where waiting is the smarter move. If rates drop significantly, say 1% or more, and stay there, you have a genuine advantage: you can refinance after buying at today’s rate. But refinancing costs money. Typically $3,000 to $5,000 in closing costs. If you save $130 per month by refinancing, you need to stay in the home 23 to 38 months just to break even on those refinance costs. The math works if you stay long enough, but it’s not the free win it sounds like. The better approach is to buy now with the understanding that you’ll refinance when it genuinely makes sense. That only works if you’re building equity in a home you own today. Sitting on the sidelines waiting for the perfect moment rarely produces the perfect moment. Waiting makes genuine sense if you can’t comfortably afford the current payment, if your job situation is uncertain, or if you’re not planning to stay in the home at least five years. Those are real reasons to wait. Fear of missing a rate drop usually isn’t.

Auburn WA Housing Market: What First-Time Buyers Find Right Now

Auburn’s $668,000 median price is approachable on a South King County household income. The city has solid schools, real job growth, and reasonable commute access to both Seattle and Bellevue. If you’re a first-time buyer looking at King County and you haven’t seriously considered Auburn, run the numbers. The inventory is there. King County had 5,071 homes for sale in March 2026, up 37.5% from March 2025. Auburn is getting its share. Monthly supply county-wide is 2.2 months, which means buyers have real choices rather than the single-shot bidding wars of late 2024. New listings jumped 16.5% year-over-year to 3,686 county-wide in March. You’re not racing against 15 other offers on every property in Auburn right now.

How Waiting Affects Your Down Payment Strategy

One cost that doesn’t show up in the rate comparison: opportunity cost on your down payment savings. If you’re waiting for rates to drop and delaying your purchase, home prices likely keep appreciating at 2% to 4% per year in a healthy market. Every month you wait, the down payment required grows with the price. Start saving now. Get pre-qualified now. And talk to a lender about down payment assistance before assuming you need 10% or 20%. Auburn buyers have access to Washington State Housing Finance Commission programs. Home Advantage offers up to $10,000 in down payment assistance for King County buyers earning up to $147,400. The Covenant Homeownership Program provides 0% interest assistance for qualifying first-timers. first-time buyer programs King County These programs change the affordability math enough to be worth knowing about before you decide waiting is your only option.

The Scenario Nobody Talks About: What If Rates Go Up?

Here’s the part nobody wants to think about. Rates could go higher. Oil prices are volatile. Geopolitical situations change daily. If rates climb to 7% while you’re waiting for 5.5%, that $668,000 Auburn home costs $4,200 per month instead of $3,840. That’s $360 more. And prices won’t have come down in that environment. Waiting is a bet on rates falling. It’s not a guaranteed strategy.

First-Time Buyer Advantages in Auburn, Washington

The price point is approachable. Inventory is available. The 14-day median days on market gives you room to think without panic buying. And at $668,000 with 10% down at 6.38%, you’re looking at about $3,840 monthly. That’s achievable on a $120K household income with solid debt-to-income ratios. If you qualify for WSHFC assistance, the upfront cost gets meaningfully lower. That’s a strong combination for a first-time buyer entry into King County homeownership.

Frequently Asked Questions: Buying a Home in Auburn WA

Will home prices in Auburn WA go down if mortgage rates drop?

Historically, the opposite happens. When rates fall, more buyers qualify and demand increases, which pushes prices up. King County’s March 2026 median is $995,000 county-wide, with Auburn at $668,000 ‚Äî both have held despite rate pressure. A significant rate drop would likely push Auburn prices higher, not lower.

What is the median home price in Auburn, Washington in 2026?

As of March 2026, the median single-family home price in Auburn is $668,000, making it the most affordable SFR entry point among the seven major cities I track in King County. The median days on market is 14 days, which gives buyers more time than in faster markets like Sammamish (4 days).

Are there first-time buyer programs available in Auburn, WA?

Yes. Washington State Housing Finance Commission (WSHFC) offers Home Advantage, which provides up to $10,000 in down payment assistance for King County buyers earning up to $147,400. The Covenant Homeownership Program offers 0% interest down payment loans for qualifying first-timers. FHA loans with 3.5% down are also an option.

How long should I plan to stay in a home before buying makes financial sense?

Most financial advisors suggest at least five years to offset transaction costs and break even on the purchase. In Auburn specifically, if you’re planning to stay five or more years, the buy-now math almost always beats waiting for a rate drop.

What is the best neighborhood in Auburn WA for first-time buyers?

Auburn has a range of neighborhoods from near downtown to the West Hill area with views toward Puget Sound. The best fit depends on your commute patterns, school preferences, and budget. I walk these neighborhoods regularly and can walk you through where comparable homes are moving and at what prices.

Your guide to life outside Seattle.

Gregory Dorrell | Coldwell Banker Danforth | WA License #111862
253-350-0045 · greg@livingoutsideseattle.com · www.livingoutsideseattle.com

Gregory Dorrell is a licensed real estate broker (WA License #111862) with Coldwell Banker Danforth. This post is provided for informational purposes and does not constitute financial or investment advice. Property prices, interest rates, and market conditions are subject to change. Please consult with a mortgage lender for pre-qualification information and a real estate professional for market-specific advice.